
Taxation of Funds & Tax Harvesting
1. What you'll learn and why it matters
Chapter 13 covered how shares, F&O and dividends are taxed. Funds follow the same broad logic, but with their own twists. A debt fund bought in 2024 is taxed differently from the same fund bought in 2022. A gold ETF and a gold fund holding the same gold need different holding periods. An SWP and an IDCW plan can pay you the same cash and leave very different tax bills. Fund rules have also changed four times since 2023, so much of what you read online is out of date.
By the end of this chapter you will be able to:
- put any fund or ETF into one of three tax classes for tax year 2026-27, using a three-question flowchart;
- work out the tax on any redemption lot by lot (each SIP instalment is a separate purchase), including grandfathered units bought before February 2018;
- spot the events that are taxable sales even though no cash reaches you: switches, STPs, regular-to-direct moves;
- choose between IDCW (payouts) and growth + SWP (planned withdrawals), and between arbitrage funds, liquid funds and FDs, for your slab;
- run LTCG harvesting and tax-loss harvesting correctly, and know the cases where they do not pay;
- decide whether ELSS, NPS and other tax-saving products still make sense for you under the new regime;
- compute a full year's tax for a realistic portfolio, then cut it.
On a ₹10,000 monthly SIP in a Nifty 50 index fund held since 2016, harvesting gains each March would have cut the tax due on 30 Sep 2026 from ₹1,04,470 to ₹17,237 (part 10). In the full worked year in part 17, the same investments with five tax-aware choices pay ₹1,15,991 less tax that year. None of this needs more risk or a better fund. It needs knowing the rules.
This chapter teaches the rules as they stand for tax year 2026-27 (1 Apr 2026 – 31 Mar 2027), checked against the Income-tax Act, 2025 and official sources on 2 Oct 2026. Rules change in every Budget. The fund names are real examples chosen for data, not recommendations. For large amounts, NRI status, gifts within the family or anything unusual, consult a chartered accountant (CA).
This chapter assumes you have read Chapter 13, parts 5–9 (slabs, the new regime, STCG/LTCG on shares, grandfathering, set-off). Fund basics (NAV, direct and regular plans, expense ratio, ETFs, debt fund types) are in Chapter 14. Asset allocation and tax-aware rebalancing follow in Chapter 16.
Section numbers. From 1 April 2026 the Income-tax Act, 2025 replaced the 1961 Act (Chapter 13 explains the switch). Rates carried over, but section numbers changed. Brokers, AMC statements and most articles still use the old numbers, so we give both, e.g. "s.76 (old s.50AA)".
2. Why funds are taxed differently: the pass-through
A mutual fund pools money from many investors and buys securities with it. Inside the fund, the manager buys and sells constantly: rebalancing an index, switching from one bond to another, moving between equity and debt in a balanced-advantage fund. If you made the same trades yourself, each sale would be a taxable event for you.
The law treats a SEBI-registered mutual fund as a pass-through: the fund's own income and gains are exempt (Schedule VII of the new Act, Table Sl. 20–21, old s.10(23D)). You pay tax only when you sell (redeem) units, or when the fund pays you an IDCW (income distribution). All the trading inside the fund is invisible to your tax return. The gain simply shows up in the NAV, and you are taxed on it once, when you exit.
Two consequences matter in practice:
- Deferral. Gains inside the fund compound untaxed until you redeem. Money that would have gone to tax keeps earning.
- The fund's class decides your rate, not what it holds on the day. A fund that keeps at least 65% in Indian equity is taxed entirely as equity, even though up to 35% of it may be bonds. If you held the same bonds directly, or in a separate debt fund, their gains would be taxed at your slab rate.
Same 65/35 portfolio, rebalanced every January: do it yourself, or let a fund do it?
₹50 lakh is invested on 4 Jan 2016: 65% in a Nifty 50 index fund, 35% in a liquid fund. Every January the portfolio is reset to 65/35. We apply today's rules to the whole period (30% slab, equity gains with the yearly exemption, liquid-fund gains at slab), so the only difference between the two versions is who does the rebalancing.
- DIY. Each January you redeem the asset that is above its target weight and pay tax on the gain. Over ten rebalances you pay ₹31,640 (mostly in 2022 and 2024, after strong equity years). On 30 Sep 2026 the holdings are worth ₹1,35,81,579. Selling everything then costs ₹13,72,221 in tax, because the liquid-fund gains are taxed at 30%. You keep ₹1,22,09,358.
- Inside one fund. The same trades happen inside an aggressive-hybrid-style fund. No tax until exit. The value is ₹1,36,23,010 (a little higher, because no tax left the portfolio along the way). Because the fund holds at least 65% equity, the whole gain is equity LTCG: tax = 12.5% × (gain − ₹1,25,000) × 1.04 = ₹11,04,741. You keep ₹1,25,18,269.
- Difference: ₹3,08,910 in favour of the fund. About ₹41,000 comes from not paying tax along the way. The rest comes from the fund's equity tax class applying to its debt part too.
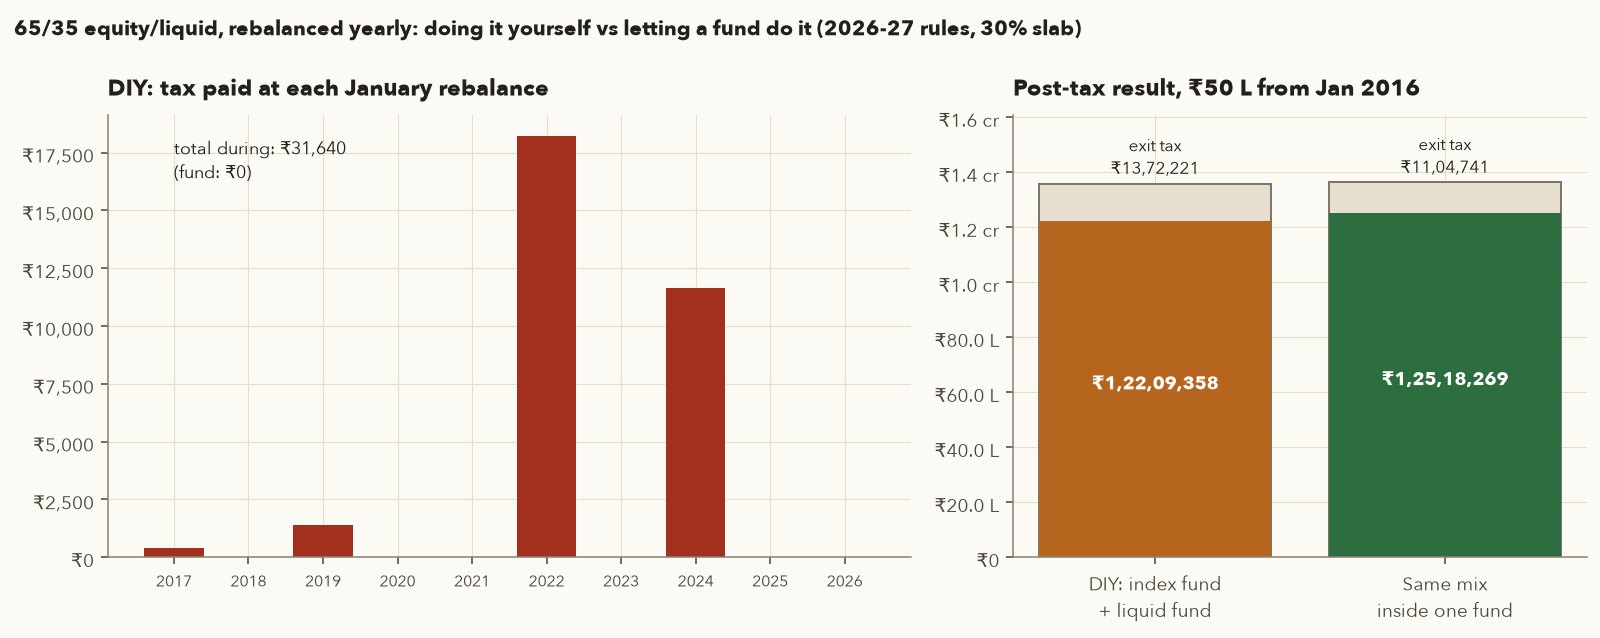
course/scripts/ch15_figures.py.Do not churn between funds. Each switch you make is taxable, while the same reshuffling inside a fund is not. A multi-asset or balanced-advantage fund can be a tax-efficient way to rebalance automatically. Read its tax class first, because some are taxed as equity and some are not (part 3). Chapter 16 covers rebalancing with new money, which avoids selling at all.
Common mistakes. (1) Assuming a fund's dividends from the shares it holds reach you as dividends. They do not: they stay in the NAV unless the fund declares an IDCW. (2) Thinking a "hybrid" is always taxed as equity. Only if it holds at least 65% in Indian equity.
3. The three tax classes for 2026-27
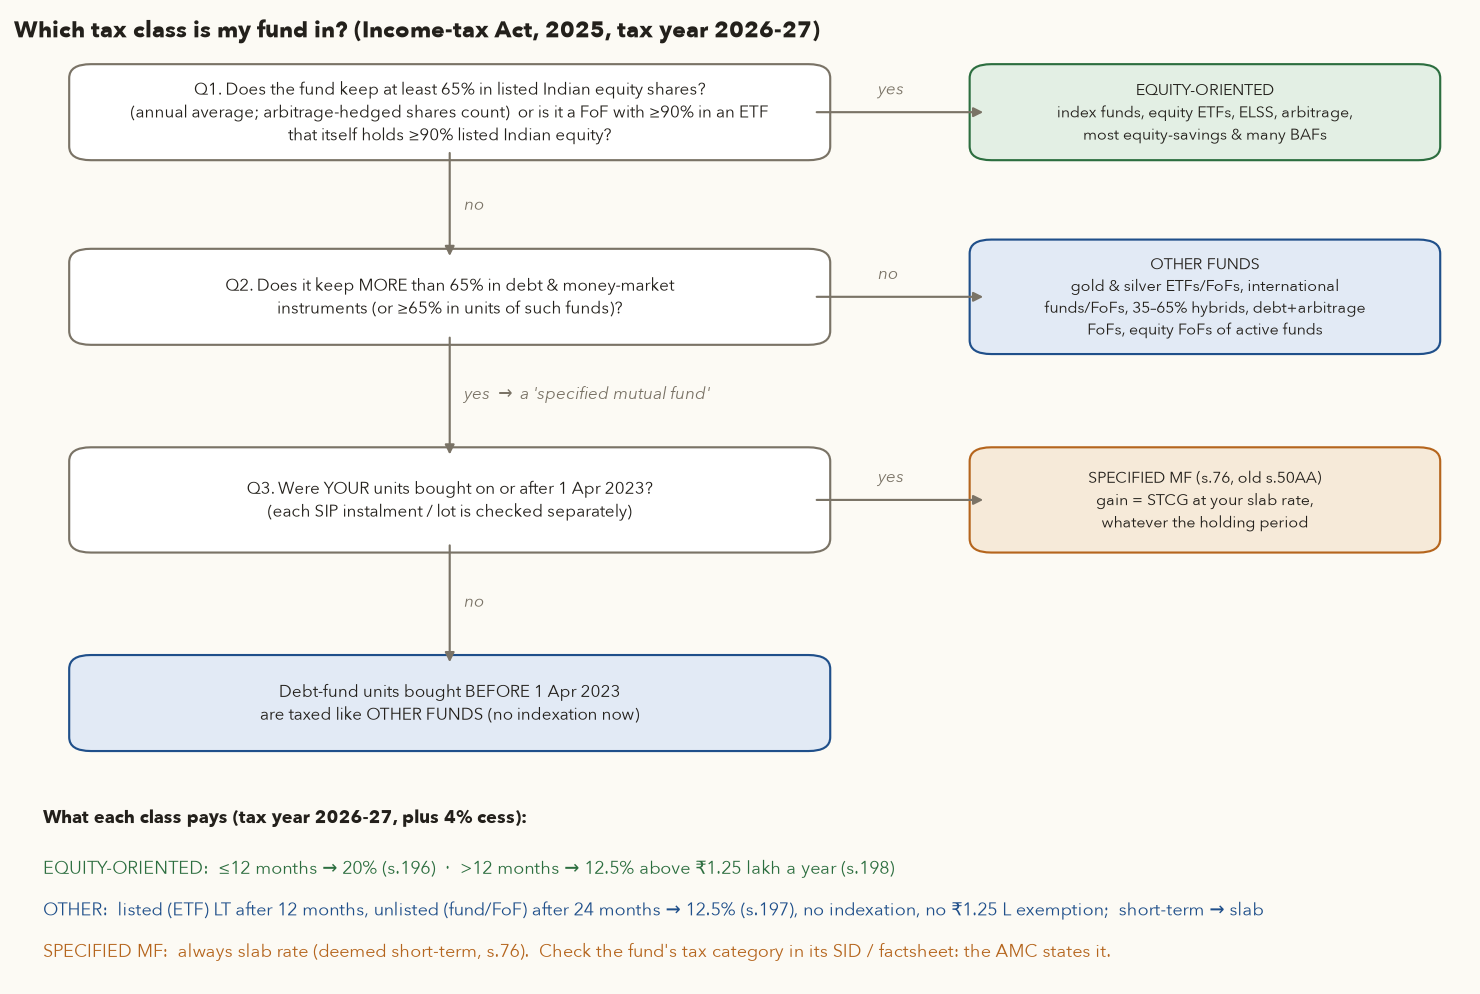
For tax purposes, every fund unit you sell in tax year 2026-27 belongs to one of three classes. The class depends on what the fund holds (its portfolio, averaged over the year) and, for debt funds only, on when you bought that unit.
Class 1: equity-oriented funds
A fund is equity-oriented if it keeps at least 65% of its money in equity shares of Indian companies listed on a recognised exchange, measured as the average over the year (s.198(8), old s.112A). Equity shares that are hedged with futures still count, which is why arbitrage funds qualify. So do most equity-savings funds and many balanced-advantage funds (BAFs), which hold over 65% "gross" equity and hedge part of it. A fund of funds (FoF) qualifies only if it puts at least 90% into units of an exchange-traded fund (ETF) that itself holds at least 90% listed Indian equity. A FoF that buys active equity funds does not qualify and falls into the "other" class.
Includes: equity funds, ELSS, Nifty/Sensex index funds, equity ETFs such as NIFTYBEES, arbitrage funds. Taxed exactly like listed shares: see the master table.
Class 2: specified mutual funds (debt), units bought from 1 Apr 2023
A specified mutual fund is one that keeps more than 65% in debt and money-market instruments (by the annual average of daily figures), or a FoF with 65% or more in such funds (s.76(5), old s.50AA). For units acquired on or after 1 April 2023, any gain is "deemed" short-term and taxed at your slab rate, however long you hold. No LTCG, no indexation, no exemption.
Includes: liquid, overnight, money-market, corporate-bond, gilt, banking & PSU, conservative-hybrid funds, debt ETFs such as LIQUIDBEES, and debt FoFs.
Class 3: other funds
Everything that is neither: gold and silver ETFs and FoFs, international funds, FoFs and ETFs (US, global), equity FoFs of active funds, hybrids holding 35–65% Indian equity, multi-asset funds below 65% Indian equity, and the newer income-plus-arbitrage FoFs (at most 65% in debt funds, the rest in arbitrage funds, built to land here). Debt-fund units bought before 1 April 2023 are also taxed as "other".
Gains are long-term after more than 12 months if the unit is listed (an ETF) and after more than 24 months if it is unlisted (a regular fund or FoF). LTCG is taxed at 12.5% with no indexation and no ₹1.25 lakh exemption (s.197, old s.112). Short-term gains go at your slab rate.
| Class | Long-term after | STCG | LTCG | ₹1.25 L exemption? | Section (new / old) |
|---|---|---|---|---|---|
| Equity-oriented (incl. equity ETFs, index funds, ELSS, arbitrage) | > 12 months | 20% | 12.5% above ₹1.25 L | Yes, shared with listed shares | s.196 / 111A; s.198 / 112A |
| Specified MF, units bought on/after 1 Apr 2023 (> 65% debt) | never | slab | n/a | No | s.76 / 50AA |
| Other, listed: gold, silver and international ETFs; debt-ETF units bought before Apr 2023 | > 12 months | slab | 12.5% | No | s.197 / 112 |
| Other, unlisted: gold and international FoFs, 35–65% hybrids; debt-fund units bought before Apr 2023 | > 24 months | slab | 12.5% | No | s.197 / 112 |
| IDCW (dividend) from any fund | n/a | slab, as "other sources"; 10% TDS above ₹10,000/yr per fund house | No | s.393(1) Sl. 4 / 194K | |
Add 4% health and education cess to every rate. Surcharge applies only above ₹50 lakh of income; on gains under s.196–198 it is capped at 15%, but slab-taxed debt-fund gains carry the full surcharge (up to 25% in the new regime). Tax year 2026-27 rules; unchanged by Budget 2026.
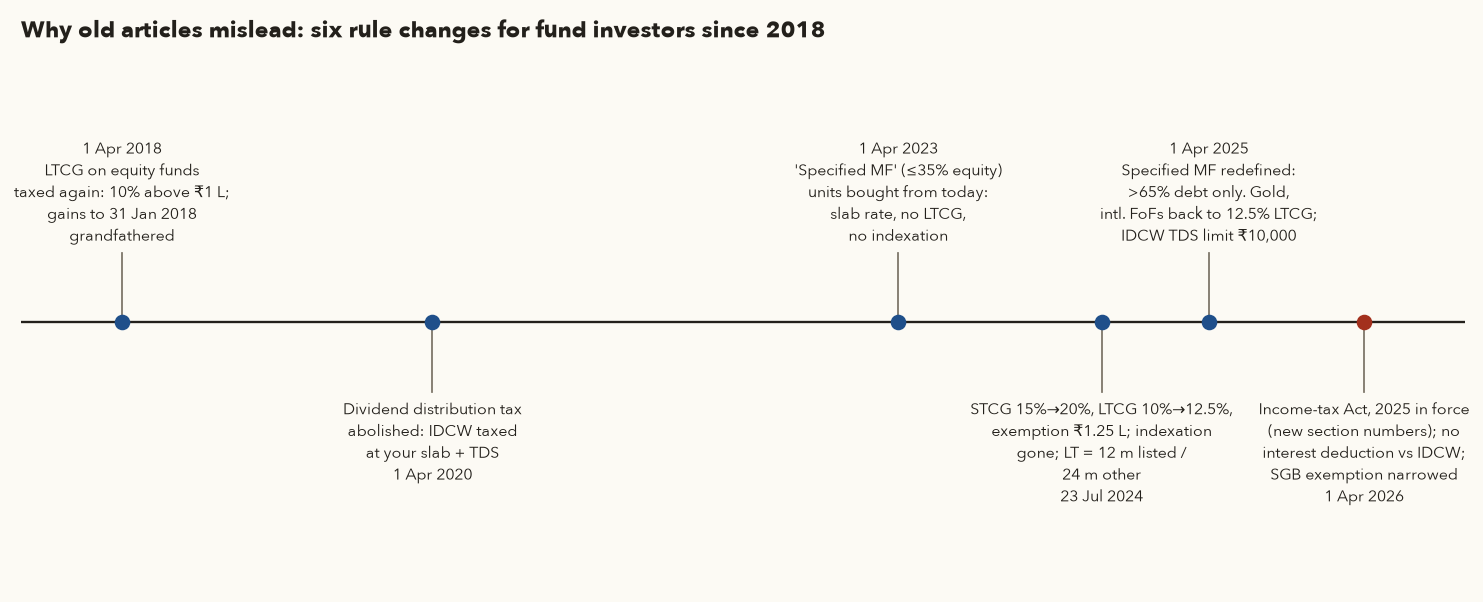
From 1 Apr 2023 to 31 Mar 2025, the "specified MF" net was much wider: any fund with no more than 35% Indian equity. That caught gold funds, international funds and FoFs, so their gains were taxed at slab too. From 1 Apr 2025 the test became "more than 65% in debt" (Finance (No. 2) Act, 2024). The test is applied when you sell, so a gold ETF bought in 2023 and sold now is back in the "other" class: 12.5% LTCG after 12 months.
Same gold, different wrapper, different tax
Two investors each put ₹2,30,160 into gold on 1 Apr 2025 and sell on 15 Sep 2026 (17.5 months later).
- ETF: 3,000 units of GOLDBEES bought at ₹76.72, sold at ₹123.62. Gain = 3,000 × (123.62 − 76.72) = ₹1,40,700. Listed, held more than 12 months: LTCG at 12.5%. Tax = 1,40,700 × 12.5% × 1.04 = ₹18,291.
- Fund of funds: Nippon India Gold Savings Fund (Direct), bought at NAV ₹37.0487, sold at ₹59.5738. Gain = ₹1,39,916. Unlisted, held less than 24 months: STCG at slab. Tax at 30% slab = ₹43,654; at 20% slab = ₹29,102.
- The FoF investor would have needed to hold until after 1 Apr 2027 for the 12.5% rate.
The purchase date decides the debt-fund rate
| Lot | Invested | Buy NAV | Units | Sell NAV | Gain | Class | Tax |
|---|---|---|---|---|---|---|---|
| 15 Jun 2022 | 4,00,000 | 26.1026 | 15,323.378 | 34.8444 | 1,33,933.91 | Other, held 48 months: LTCG 12.5% | 17,411.41 |
| 14 Jun 2024 | 4,00,000 | 30.3492 | 13,179.260 | 34.8444 | 59,223.41 | Specified MF: slab | 12,318.47 at 20%; 18,477.70 at 30% |
Units are bought for the amount less 0.005% stamp duty, so 4,00,000 × 0.99995 ÷ 26.1026 = 15,323.378 units. The 2022 lot is taxed at 12.5% + cess = 13%, with no indexation: until 22 Jul 2024 it would have been 20% after adjusting cost for inflation. The 2024 lot pays your full slab rate even though it was held two years.
How to use this. Before buying any fund, find its tax class in the scheme information document (SID) or ask the AMC. For debt, a fund bought after April 2023 is no more tax-efficient than an FD. Its advantages are elsewhere: liquidity, no tax until you redeem (an FD's interest is taxed every year as it accrues) and the ability to offset losses (part 9).
Common mistakes. Calling every hybrid "equity" (check the 65%); assuming international FoFs get the 12-month rule (only listed ETFs do); treating your 2022 debt units like your 2024 ones; using indexation in a post-July-2024 sale.
4. Holding periods, the exemption, indexation and grandfathering
Holding period. "Long-term" means held for more than 12 (or 24) months, counted from the allotment date to the redemption date (s.2(101), old s.2(42A)). A unit allotted on 5 Sep 2025 becomes long-term on 6 Sep 2026, not 5 Sep 2026. For a mutual fund, the allotment date is the date whose NAV you got. For an ETF, it is the trade date.
The ₹1.25 lakh exemption is per person, per tax year, and shared between listed shares, equity funds and equity ETFs (s.198). It is applied after set-off of losses (part 9), and unused exemption is lost at 31 March. Since Budget 2025, the ₹12 lakh rebate of the new regime (s.156, old s.87A) cannot be used against tax on these special-rate gains (Chapter 13, part 5). It does cover slab-taxed debt-fund gains, which matters for low-income family members (part 12).
No indexation. Indexation raised your cost by the inflation index. It was removed for every fund sale from 23 Jul 2024. It survives only for land and buildings bought before that date.
- \(T\)
- The tax for the year on these gains, in ₹.
- STCG
- The year's net short-term gain from equity-oriented funds and equity ETFs (units held 12 months or less), in ₹, after setting off losses.
- LTCG
- The year's net long-term gain (held more than 12 months), in ₹, after setting off losses.
- \(0.20,\ 0.125\)
- The 20% STCG rate and the 12.5% LTCG rate.
- \(1{,}25{,}000\)
- The ₹1.25 lakh yearly exemption, shared with your listed shares.
- \(\max(0,\ \dots)\)
- "The larger of 0 and the bracket": LTCG below ₹1.25 lakh gives 0 taxable, never a negative number.
- \(1.04\)
- Adds the 4% health and education cess.
- Short-term part: 20% of STCG.
- Long-term part: knock ₹1.25 lakh off the LTCG (stopping at zero) and take 12.5% of what is left.
- Add the two and multiply by 1.04 for cess.
- Other classes work differently. Other-class LTCG gets no exemption: \( T = 1.04 \times 0.125 \times \text{LTCG} \). Specified-MF gains, and other-class STCG, are simply added to your slab income.
Example (illustrative): STCG ₹50,000 and LTCG ₹2,00,000 in one year. \(T = 1.04 \times [0.20 \times 50{,}000 + 0.125 \times 75{,}000] = 1.04 \times 19{,}375 = ₹20{,}150\). Other class, from part 3: the GOLDBEES gain of ₹1,40,700 pays 1,40,700 × 0.125 × 1.04 = ₹18,291.
Grandfathering for equity-fund units bought before 1 Feb 2018
Equity LTCG was fully tax-free until 31 Mar 2018. When it was taxed again, gains up to 31 Jan 2018 were protected. For units bought on or before 31 Jan 2018, the cost used is raised to the fair market value (FMV) on that date, but only up to the sale price (s.90(7)–(8), old s.55(2)(ac)). For mutual-fund units, the FMV is the NAV on 31 Jan 2018. For ETF units, which are listed, it is the highest traded price that day (as for shares in Chapter 13).
- \(c\)
- The cost per unit used for tax, in ₹.
- \(c_{\text{actual}}\)
- What you really paid per unit (the purchase NAV).
- \(\text{NAV}_{31\,\text{Jan}\,2018}\)
- The fair market value: the fund's NAV on 31 Jan 2018 (for an ETF, the highest traded price that day).
- \(\text{NAV}_{\text{sale}}\)
- The NAV (or ETF price) at which you redeem.
- \(\min,\ \max\)
- \(\min\) picks the smaller number in its bracket; \(\max\) picks the larger.
- Take the smaller of the 31 Jan 2018 NAV and the sale NAV. This cap means the step-up can never turn a gain into a loss.
- Take the larger of that and your actual cost. You never use a cost below what you paid.
- Taxable gain = units × (sale NAV − \(c\)). Cases A and C in the example below show both steps.
₹1,00,000 invested on 1 Jun 2016 at ₹52.0847 = 1,919.950 units
| Case | Sold | Sale NAV | Cost used | Actual gain | Taxable gain |
|---|---|---|---|---|---|
| A: sold well above FMV | 30 Sep 2026 | 159.2891 | 71.3422 (FMV) | 2,05,827.11 | 1,68,853.65 |
| B: bought above FMV (29 Jan 2018 at ₹72.0043, 1,388.806 units) | 30 Sep 2026 | 159.2891 | 72.0043 (actual) | 1,21,221.66 | 1,21,221.66 |
| C: sold between cost and FMV | 1 Jun 2020 | 65.0883 | 65.0883 (sale) | 24,966.28 | 0 |
| D: sold below cost | 23 Mar 2020 | 50.4013 | 52.0847 (actual) | −3,232.02 | −3,232.02 (loss kept) |
- Case A: min(71.3422, 159.2891) = 71.3422; max(52.0847, 71.3422) = 71.3422. Gain = 1,919.950 × (159.2891 − 71.3422) = ₹1,68,853.65. The ₹36,973 earned before 31 Jan 2018 is never taxed.
- Case C: min(71.3422, 65.0883) = 65.0883 = the sale price, so the gain is zero. Grandfathering removes gains; it never creates a loss.
- No stamp duty in these cases: stamp duty on MF purchases began on 1 Jul 2020.
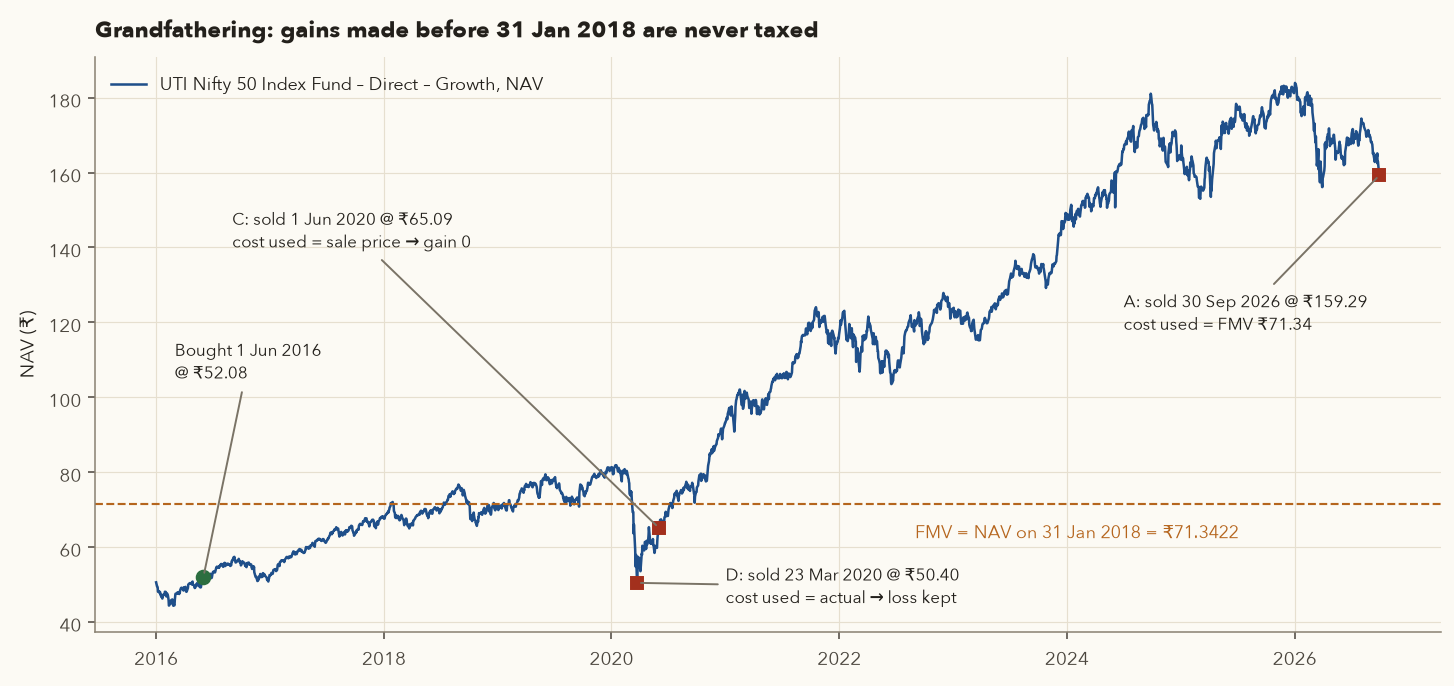
If you sell a grandfathered unit when the NAV is below its 31 Jan 2018 NAV and buy it back, the new cost is the lower sale NAV. You have thrown away the step-up to FMV. Harvest such units only when the NAV is above the FMV. The simulation in part 10 skips March 2020 for exactly this reason.
5. Lots and FIFO: how a SIP is taxed
Every purchase creates a lot: a date, a NAV and a number of units. A monthly SIP of four years creates 48 lots. When you redeem, the registrar (CAMS or KFintech) takes units first in, first out (FIFO): the oldest lot first, then the next. Each lot has its own holding period and its own gain. FIFO runs separately for each folio, each scheme, each plan (direct or regular) and each option (growth or IDCW). Your app's "average cost" is a convenience figure; tax is computed lot by lot.
- \(i\)
- Which lot (instalment): 1 is the oldest.
- \(G_i\)
- The capital gain (or loss, if negative) on the units sold from lot \(i\), in ₹.
- \(u_i\)
- Units redeemed from this lot. FIFO uses up whole lots, oldest first, so \(u_i\) is the full lot except perhaps for the last one touched.
- \(\text{NAV}_{\text{sale}}\)
- The NAV you redeem at, in ₹.
- \(\ell\)
- The exit load as a fraction (1% = 0.01), if this lot is still inside the load period; otherwise 0.
- \(A_i\)
- The amount paid for the whole lot, in ₹, stamp duty included (the full instalment).
- \(U_i\)
- Units allotted in the lot. \(A_i / U_i\) is the lot's cost per unit.
- Sale value: units sold × sale NAV, less any exit load.
- Cost: units sold × the lot's cost per unit. Because \(A_i\) includes stamp duty, the stamp duty counts as part of your cost.
- Gain = sale value − cost. STT is not deductible. Do this for every lot touched, and sort each gain into short- or long-term by that lot's own purchase date.
In the example below, the first lot (₹10,000 for 81.807 units, no load) gives \(G = 81.807 \times 159.2891 - 10{,}000 = ₹3{,}030.96\).
45 lots; you redeem ₹2,00,000 on 30 Sep 2026 at NAV ₹159.2891
- Lots. 45 instalments, ₹4,50,000 invested, 2,920.37 units, worth ₹4,65,183.75. First lot: 5 Jan 2023 at ₹122.2323 → 10,000 × 0.99995 ÷ 122.2323 = 81.807 units.
- Which lots are long-term? Those bought on or before 29 Sep 2025: 33 lots (Jan 2023 – Sep 2025). The 12 lots from Oct 2025 onward are short-term. 25 of the 45 lots are below cost, because the NAV fell from ₹183 in early 2026.
- Units to redeem. 2,00,000 ÷ 159.2891 = 1,255.58 units.
- FIFO. These come from the 16 oldest lots in full (Jan 2023 – Apr 2024) plus 54.818 of the 64.975 units of the 6 May 2024 lot. All 17 are long-term.
- Gain = 2,00,000 − cost of those units (₹1,68,436.74) = ₹31,563.26 LTCG, within the ₹1.25 lakh exemption: tax ₹0. STT = 0.001% × 2,00,000 = ₹2.
- If you had used the average cost of all 45 lots (₹154.09 per unit), you would wrongly report a gain of ₹6,528.06.
| Lot (oldest first) | NAV | Units sold | Cost | Gain | Days held |
|---|---|---|---|---|---|
| 5 Jan 2023 | 122.23 | 81.807 | 10,000.00 | 3,030.96 | 1,364 |
| 6 Feb 2023 | 120.68 | 82.859 | 10,000.00 | 3,198.54 | 1,332 |
| 6 Mar 2023 | 120.39 | 83.057 | 10,000.00 | 3,230.07 | 1,304 |
| … 13 more full lots … | |||||
| 5 Apr 2024 | 154.41 | 64.761 | 10,000.00 | 315.72 | 908 |
| 6 May 2024 (part) | 153.90 | 54.818 | 8,436.74 | 295.12 | 877 |
| Total, 17 lots | 1,255.58 | 1,68,436.74 | 31,563.26 |
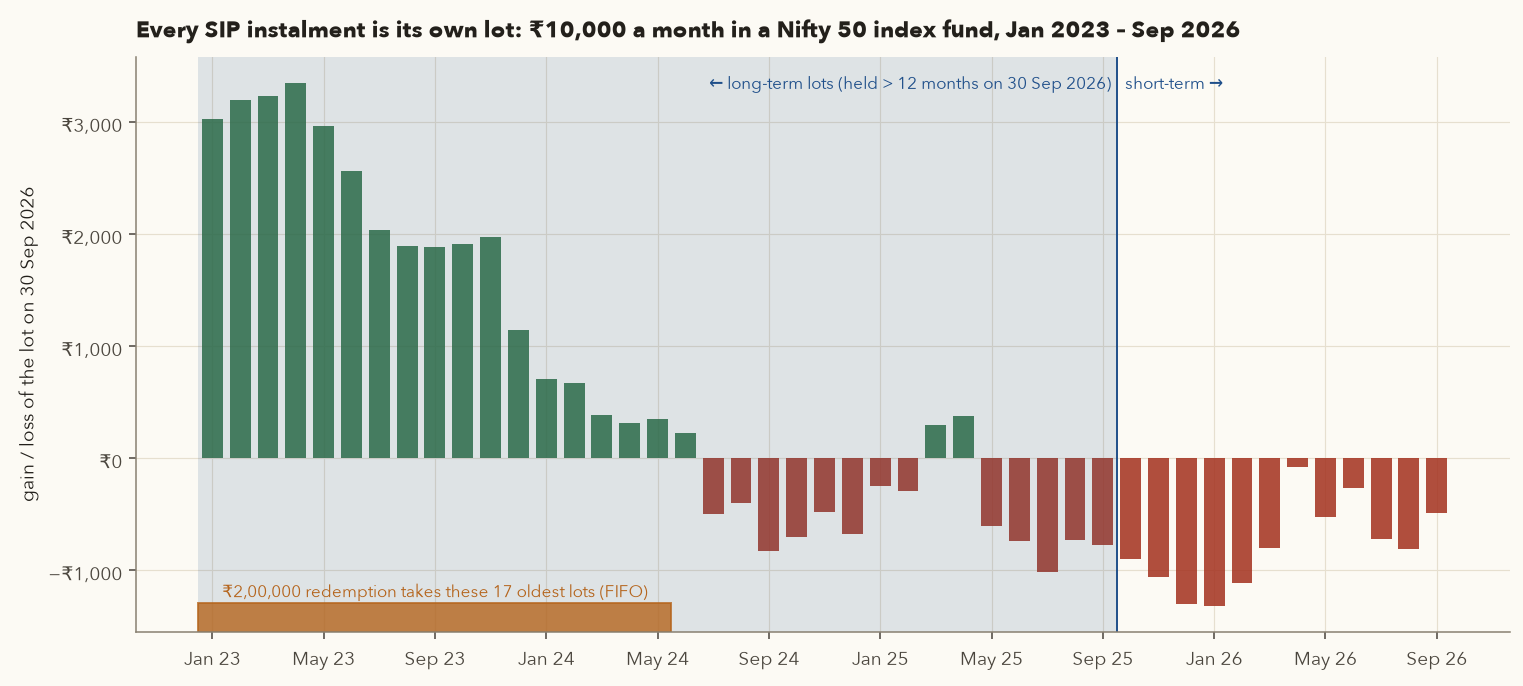
How to use this. Download the capital-gains statement from your registrar before any large redemption: it lists every lot with its date, NAV and term. If you plan to redeem soon after a SIP instalment, check whether that instalment will be in the FIFO queue (it will not, unless you redeem everything older first).
Common mistakes. (1) Expecting to redeem "the new units that are in loss" from a long SIP. FIFO will not let you: the old gain lots go first (part 11). (2) Forgetting that ELSS lock-in is also per lot: each instalment unlocks three years after its own date.
6. Switches, STP, SWP and other taxable events
A redemption is a sale. Several transactions that feel like "moving money around" are redemptions too:
- Switch from one scheme to another, even within the same fund house: redeem from A, buy B. Taxable on A's gain.
- Regular → direct in the same scheme: the two plans are different units with different NAVs, so this is a redemption of the regular units and a fresh purchase of direct units. Taxable. Exit load may apply.
- Growth ↔ IDCW option of the same scheme: also a redemption and a purchase.
- STP (systematic transfer plan): a series of switches, usually from a liquid fund into an equity fund. Each transfer redeems some liquid-fund units, so each one is taxable. For a liquid fund bought after April 2023 the small gain on each transfer is slab income.
- SWP (systematic withdrawal plan): a series of redemptions. Each withdrawal is taxed only on the gain portion of the units sold (below).
Not taxable, because the law says they are not transfers (s.70(1), old s.47):
- Scheme mergers under SEBI's consolidation process, within the same class (equity into equity, or non-equity into non-equity): units of the merging scheme become units of the merged scheme. Your cost and holding period carry over (s.70(1)(zj), s.73(1) Sl. 8, s.2(101)(c)(B)(VII)).
- Plan consolidation by the fund within a scheme (s.70(1)(zk)). This is the fund merging plans, not you switching.
- Segregated portfolio ("side pocket") units, created when a fund separates a defaulted bond. Your original cost is split between the main and segregated units in proportion to their NAVs, and the holding period carries over (s.73(1) Sl. 11–12).
- Gifts, wills and inheritance (s.70(1)(b)): part 15.
SWP: only the gain portion is taxed
When you withdraw ₹W by selling units at today's NAV, part of that money is your own capital coming back. Only the rest is gain.
- \(W\)
- The amount withdrawn this time, in ₹.
- \(c\)
- Your cost per unit, in ₹ (amount invested ÷ units allotted).
- \(\text{NAV}_t\)
- The NAV on the withdrawal date \(t\).
- \(G_w\)
- The capital gain inside this withdrawal, in ₹. The rest, \(W - G_w\), is your own money coming back and is not taxed.
How it works: \(c / \text{NAV}_t\) is the share of each rupee withdrawn that is original cost. One minus that is the share that is gain. The higher the NAV has risen above your cost, the bigger the gain portion. Units sold = \(W / \text{NAV}_t\), so this is the same as units sold × (NAV − cost). With several lots, apply it lot by lot in FIFO order.
29 withdrawals, ₹4,35,000 taken out; only ₹1,30,530 of it was gain
- Purchase: ₹10,00,000 at NAV ₹118.2387 → 8,457.045 units; cost per unit = 10,00,000 ÷ 8,457.045 = ₹118.24.
- First withdrawal, 10 May 2024 at NAV ₹151.4936: units sold = 15,000 ÷ 151.4936 = 99.01. Gain = 15,000 × (1 − 118.24 ÷ 151.4936) = ₹3,292.12. The other ₹11,708 is your money back.
- Last withdrawal, 10 Sep 2026 at ₹165.3512: 90.72 units, gain ₹4,273.32.
- Gain per tax year: FY 2024-25 ₹46,197 (11 withdrawals), FY 2025-26 ₹57,843 (12), FY 2026-27 so far ₹26,490 (6). All long-term, all inside the ₹1.25 lakh exemption: tax ₹0.
- 5,882.13 units (₹9,36,959) are still invested on 30 Sep 2026.
Even if this were a debt fund taxed at a 30% slab, the FY 2026-27 tax on the gain portion would be ₹8,265 on ₹90,000 withdrawn, far less than 30% of the cash taken out.
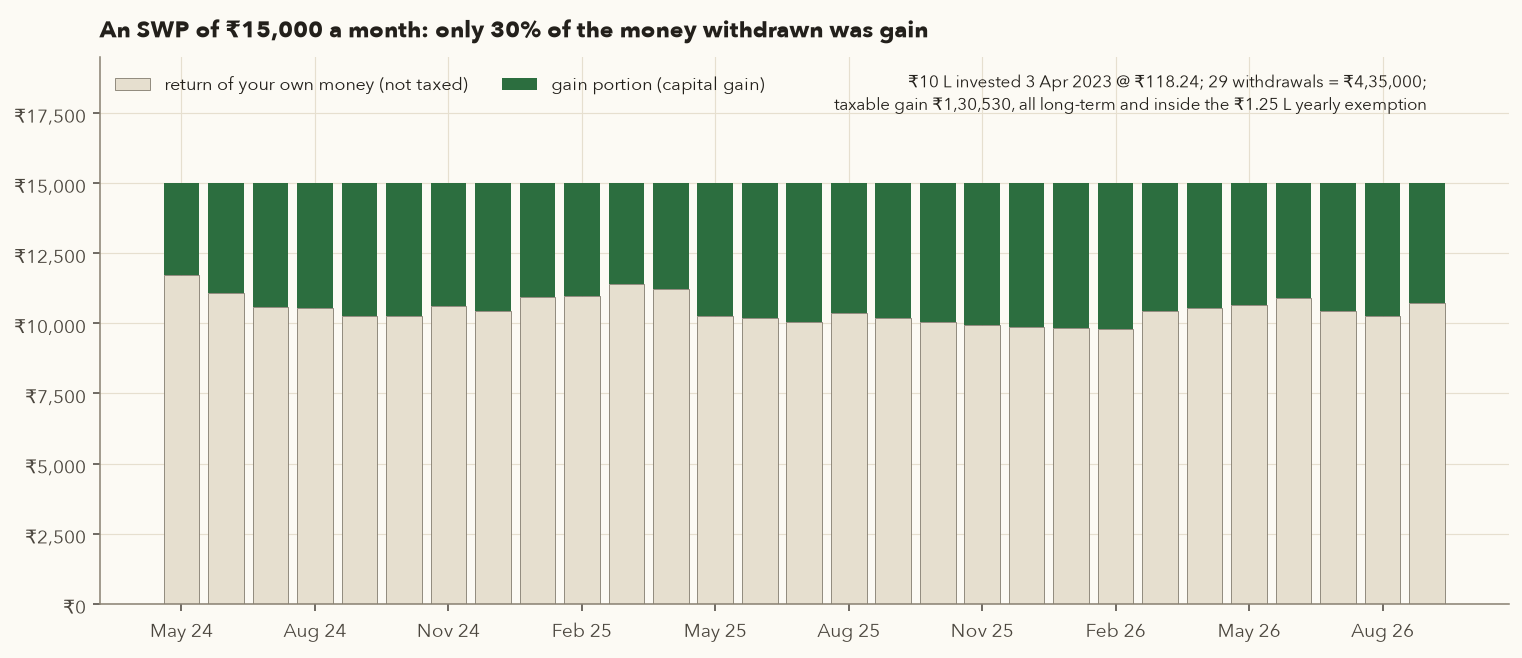
Common mistakes. Switching regular → direct in one go and paying a large LTCG bill that could have been spread across years (part 17 shows the trade-off). Starting an STP from a liquid fund without realising each transfer is a taxable redemption. Treating the whole SWP amount as income.
7. IDCW: income from funds, and why growth + SWP usually wins
IDCW (income distribution cum capital withdrawal, formerly "dividend") is money the fund pays out of its NAV. The name says what it is: partly your own capital handed back. After the record date the NAV falls by the amount paid, so you are no richer. But since 1 Apr 2020 the whole payout is taxed as your income at slab rate under "income from other sources". Two details for tax year 2026-27:
- TDS: the fund house deducts 10% if its IDCW payments to you exceed ₹10,000 in the tax year (s.393(1) Table Sl. 4(i), old s.194K; the limit was ₹5,000 until March 2025). Once you cross ₹10,000, TDS applies on the whole amount. TDS is a credit against your tax, not the final tax.
- No deductions: from tax year 2026-27, no expense (not even interest on money borrowed to invest) can be set against IDCW or dividend income (s.93, as amended by Budget 2026; see Chapter 13, part 10).
An SWP from the growth option of the same fund gives you the same cash, but taxed only on the gain portion, at capital-gains rates, and inside the ₹1.25 lakh exemption if the fund is equity-oriented.
Monthly IDCW of ₹0.07 per unit versus the same cash by SWP, Oct 2025 – Sep 2026
- IDCW plan: ₹30,00,000 at NAV ₹20.23 → 1,48,287.20 units. The fund declared ₹0.07 per unit every month (confirmed in AMC notices for March, April and June 2026; our NAV-based check for the other months gives ₹0.07–0.08). Payout = 1,48,287.20 × 0.07 = ₹10,380.10 a month; 12 payouts = ₹1,24,561 a year.
- Tax on IDCW: at 30% slab, 1,24,561 × 0.30 × 1.04 = ₹38,863; at 20% slab, ₹25,909. TDS of ₹12,456 is deducted along the way.
- Growth plan: the same ₹30 lakh at NAV ₹57.96 → 51,757.25 units. Withdraw ₹10,380.10 on each IDCW date. The gain portion of the 12 withdrawals is ₹40,962 (32.9% of the cash), all long-term.
- Tax on SWP: ₹0 if the exemption is unused; even if it is fully used elsewhere, 40,962 × 12.5% × 1.04 = ₹5,325.
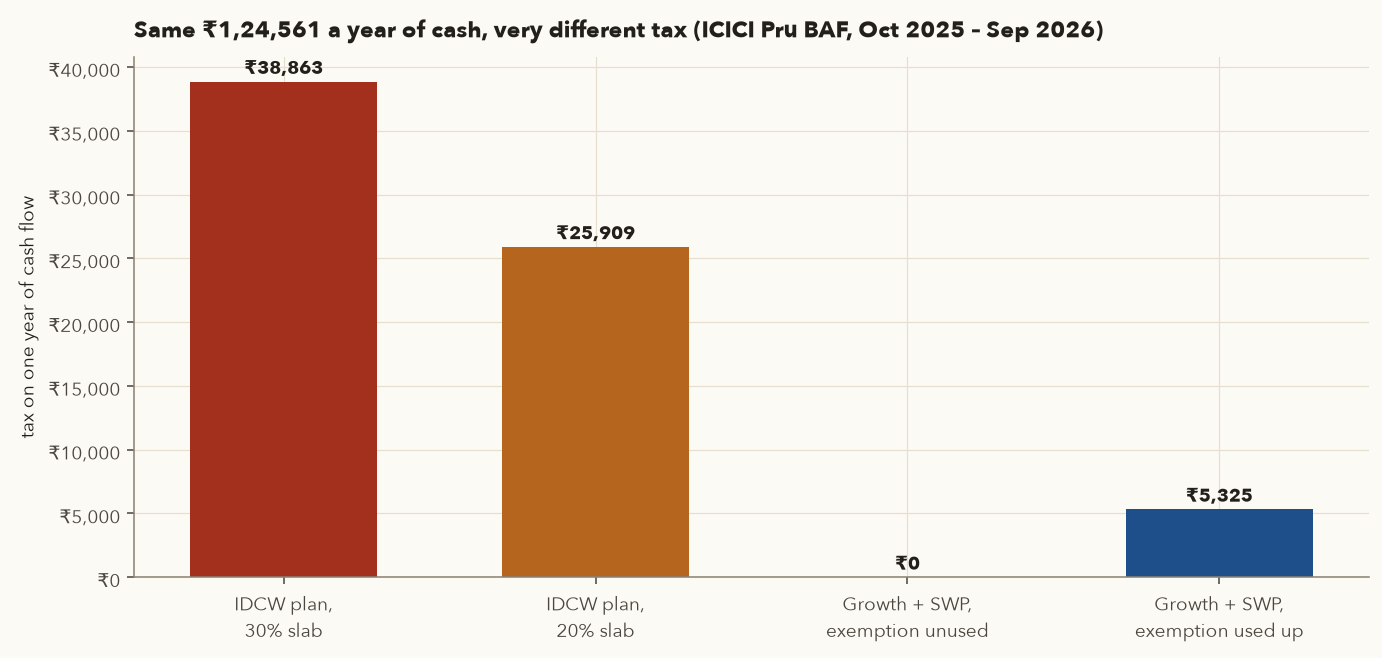
When IDCW can make sense: if your total income stays within the ₹12 lakh rebate limit, slab-taxed IDCW may cost nothing. Some investors also value the discipline of fixed payouts. Even then, an SWP can be set to a fixed amount and date.
Common mistakes. Choosing IDCW "for regular income" in a high slab; reinvesting IDCW (IDCW reinvestment) and still paying tax on it; switching an old IDCW holding to growth without checking the capital gain on the switch.
8. ETFs versus mutual funds: STT, stamp duty, exit loads
For the same index, an ETF and an index fund are in the same tax class with the same rates. Equity funds and equity ETFs share the 12-month rule. For "other" funds the ETF's listing gives it the shorter 12-month rule (the gold example in part 3). The transaction charges differ:
| Charge | Mutual fund (bought from the AMC) | ETF (bought on the exchange) |
|---|---|---|
| STT | 0.001% on redemption of equity-oriented units; none on purchase; none for non-equity funds | 0.001% on the sell side for equity ETFs; none on purchase; none for gold, debt or international ETFs |
| Stamp duty | 0.005% on every purchase (SIP, switch-in, STP-in, IDCW reinvestment), since 1 Jul 2020 | 0.015% on purchase, as for delivery shares |
| Brokerage, exchange & SEBI fees, GST, DP charge | None for direct plans | As for shares (Chapter 13, part 2); DP charge per sell day |
| Exit load | Scheme-specific; most index funds nil, many active funds 1% within 1 year | None (but you pay the bid-ask spread and any premium to NAV) |
| Tax treatment of the charges | Stamp duty, brokerage and other charges count as cost or sale expenses. Exit load reduces your sale value. STT is not deductible for capital gains. | |
What does a sell-and-rebuy cost?
- Index fund: STT 0.001% × 3,22,111 = ₹3.22; stamp duty on the re-purchase 0.005% = ₹16.11. Total ₹19.33.
- ETF at Zerodha-listed rates: STT ₹3.22, stamp ₹48.32, exchange charges ₹19.78, SEBI fee ₹0.64, GST ₹3.68, DP ₹15.34. Total ₹90.98, plus the spread. Still tiny next to the ₹16,250 of tax a full harvest saves.
ETF switches. There is no "switch" for an ETF: you sell on the exchange (a taxable sale) and buy another. For ETFs, sell one day and buy back the next trading day. A same-day sell and buy of the same ETF nets off as an intraday trade and does not reset your cost (Chapter 13, part 14).
9. Set-off and carry-forward with funds
The general rules are in Chapter 13, part 9: a short-term capital loss (STCL) can absorb any capital gain; a long-term capital loss (LTCL) only long-term gains; both carry forward for 8 tax years if you file your return by the due date. What is specific to funds:
- A gain on a specified MF is legally a short-term capital gain (s.76), so an STCL from shares or equity funds can absorb it. That is the most valuable use of an STCL: it cancels income that would otherwise be taxed at your slab rate (up to 31.2%).
- A loss on a specified MF is an STCL too, so it can absorb any gain, including equity LTCG.
- An LTCL (say from a gold ETF or a fund in loss) can absorb other-class LTCG (12.5% with no exemption) or equity LTCG. Equity LTCG under ₹1.25 lakh would have been tax-free anyway, but the law requires set-off before the exemption. When you have a choice, set the LTCL against the 12.5% gains with no exemption first.
- Capital losses never reduce salary, IDCW or interest income.
- You may set off in the order that suits you (STCL against slab-rate gains first). The ITR schedules let you allocate; check what your CA or tax software does.
Where should a share loss go?
Chapter 13's ITC sale produced an STCL of ₹7,797.50 and an LTCL of ₹16,130. Suppose the same year has the slab-taxed debt-fund gain of ₹59,223 (part 3) and the GOLDBEES LTCG of ₹1,40,700.
- STCL against the debt-fund gain at a 20% slab: saves 7,797.50 × 20% × 1.04 = ₹1,621.88. Against equity STCG it would save the same 20.8%; at a 30% slab it would save 31.2%.
- LTCL against the gold LTCG: saves 16,130 × 12.5% × 1.04 = ₹2,096.90. Against equity LTCG that is inside the ₹1.25 lakh exemption it would save nothing.
10. LTCG harvesting in depth
LTCG harvesting means selling long-term equity-fund units each year to realise gains up to the unused ₹1.25 lakh exemption, then buying back. The tax on that ₹1.25 lakh is zero, and the re-purchase resets your cost higher, so that gain is never taxed later. Chapter 13 showed it with NIFTYBEES. Here is the fund version, with its extra details.
- \(E\)
- The part of this year's ₹1.25 lakh exemption you have not used yet, in ₹ (after any other LTCG from shares or funds this year).
- \(\text{NAV}_t\)
- Today's NAV, in ₹.
- \(c\)
- The lot's cost per unit, in ₹ (the grandfathered cost for pre-Feb-2018 lots).
- \(\text{NAV}_t - c\)
- The gain on each unit if sold today.
- \(u^{*}\)
- The number of units to sell so that the booked gain is exactly \(E\).
- \(0.125 \times 1.04\)
- The 12.5% LTCG rate plus 4% cess, i.e. 13%.
- Divide the exemption left by the gain per unit. That many units books exactly \(E\) of gain, tax-free.
- If the oldest lot has fewer units than \(u^{*}\), sell all of it, subtract its gain from \(E\), and repeat with the next lot (FIFO).
- Buy back the same amount. The ₹\(E\) of gain is now in your cost, so it is never taxed. At 13%, a full ₹1.25 lakh harvest saves ₹16,250 of future tax.
Example (illustrative \(E\) = ₹3,000 left): the SIP's 5 Jan 2023 lot cost 10,000 ÷ 81.807 = ₹122.24 a unit. At NAV ₹159.2891, \(u^{*} = 3{,}000 / (159.2891 - 122.24) = 80.97\) units, which the 81.807-unit lot can cover.
Harvest every March versus never selling
129 instalments, ₹12,90,000 invested. "Harvest" means: on the first NAV day on or after 20 March each year, redeem long-term lots FIFO until the year's limit is booked (₹1 lakh up to FY 2023-24, ₹1.25 lakh from FY 2024-25), stopping at the first lot with no gain, and buy back the same day using cash from your bank (the redemption money refills it two days later). Grandfathering applies to the 2016–Jan 2018 lots.
- March 2019: only ₹20,856 could be booked. The oldest lots were grandfathered at ₹71.34 and the NAV was ₹75.55, so they carried little taxable gain.
- March 2020: skipped. The NAV (₹57.86) was below the 31 Jan 2018 FMV, and selling grandfathered lots would have destroyed their step-up.
- 2021–2024: ₹1,00,000 booked each March. 2025 and 2026: ₹1,25,000 each. Total booked tax-free: ₹6,70,856.
- Result on 30 Sep 2026 (value ≈ ₹22.85 lakh in both cases): never harvested, the long-term gain is ₹9,37,983 and the tax if all were sold is (9,37,983 − 9,370 short-term loss − 1,25,000) × 12.5% × 1.04 = ₹1,04,470. Harvested, the long-term gain is ₹2,72,215 and the tax is ₹17,237.
- Extra charges over seven harvests: ₹136. Post-tax wealth is ₹87,045 higher.
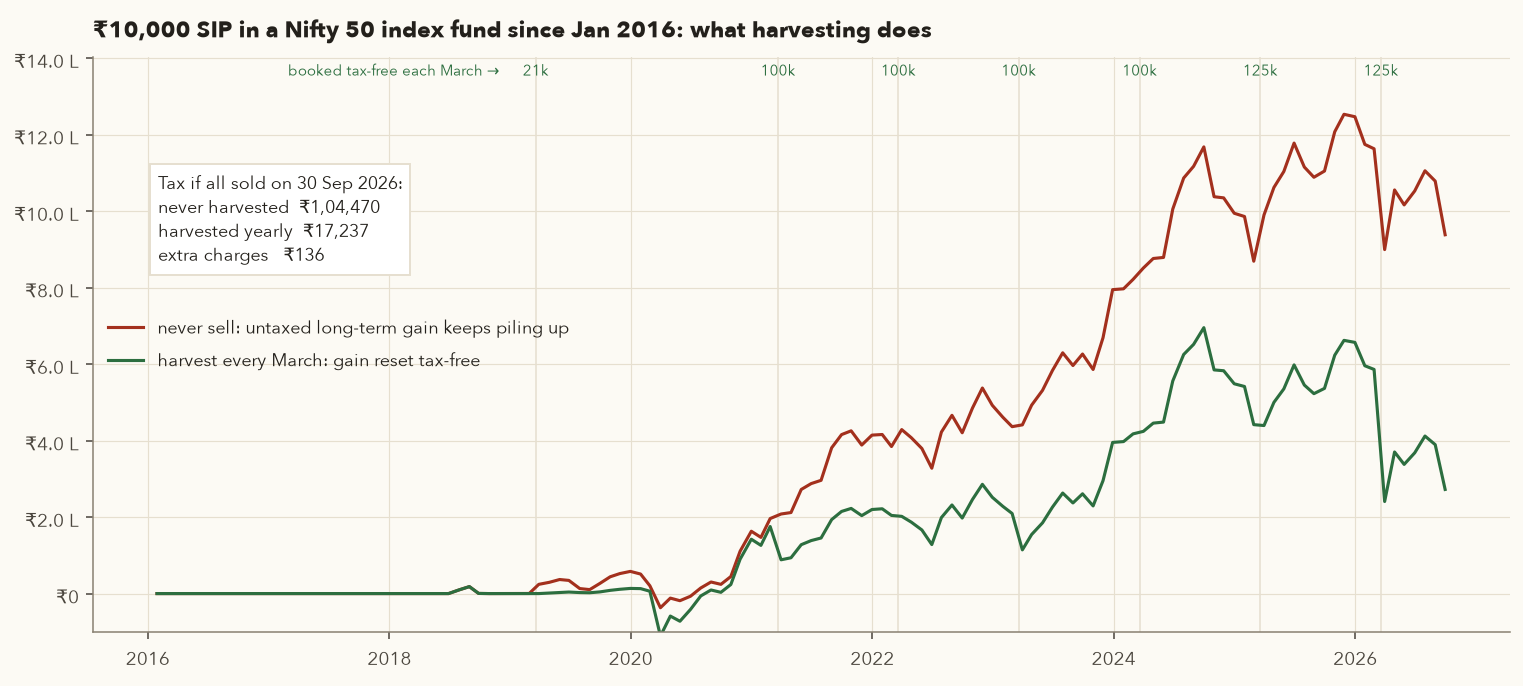
course/scripts/ch15_figures.py.The fine print
- Clock reset. The re-bought units are short-term for 12 months. If you might need the money within a year, that portion would be taxed at 20% if sold.
- Exit load. Most index funds have none. Many active funds charge 1% within a year, and some charge for longer. Re-bought units restart the exit-load clock too.
- Same day or next day? For mutual funds you can redeem and buy on the same day, and there is no intraday netting for fund units. The redemption gets that day's NAV if placed before the 3 pm cut-off. The purchase gets that day's NAV only if your money reaches the fund house before the cut-off (SEBI ties purchase NAV to when funds are realised), so pay from your bank early in the day. A purchase a day later is also fine; you just carry one day of market move. For ETFs, buy back the next trading day (part 8).
- The exemption is shared with shares and equity ETFs. Add up your year's LTCG before you harvest.
- FIFO decides which units go. You cannot pick a high-cost lot to harvest.
When harvesting does not pay: exit loads
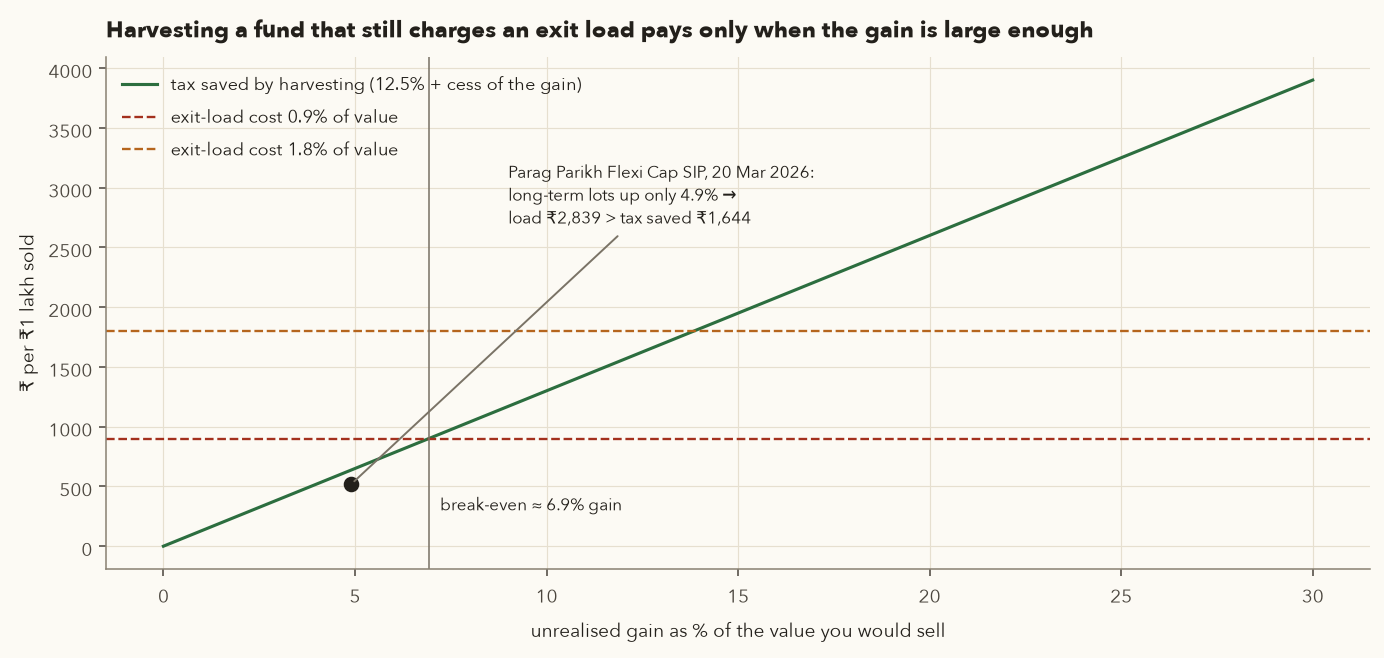
A 1% exit load can cost more than the tax saved
This fund charges 2% within 365 days and 1% from 366 to 730 days, on units above 10% of each purchase. On 20 Mar 2026 (NAV ₹87.7908) the 12 long-term lots (Apr 2024 – Mar 2025, ₹3,00,000 invested) were all 12–24 months old.
- Their value was ₹3,15,486 and the gain before load ₹15,486 (4.9%).
- Exit load on 90% of the units at 1% = ₹2,839. Gain booked after load = ₹12,647.
- Tax saved = 12,647 × 12.5% × 1.04 = ₹1,644. Net result: −₹1,195. Harvesting lost money, and the re-bought units would face a 2% load for a year.
Break-even, roughly: with a 0.9% effective load, the gain must exceed 0.9% ÷ 13% ≈ 6.9% of the value sold. Counted the strict way used in step 3, where the load also shrinks the gain you book, the line is a little higher, about 7.8%. Either way, wait until the lots are past the load period (here, 730 days).
Couples: two PANs, two exemptions, and clubbing
The exemption is per person. If the same SIP had been split between two spouses, each investing their own income (₹5,000 a month each) and each harvesting their own ₹1–1.25 lakh, the tax due on 30 Sep 2026 would be ₹0 instead of ₹17,237, a further ₹17,056 better than one harvesting investor.
If you give your spouse money (or units) and they invest it, the income from that asset, including capital gains, is clubbed into your income (s.99(1)(a)(ii), old s.64(1)(iv)). The gains are then yours, and so is the single exemption. Two exemptions work only when each spouse invests their own earnings. Gifts to adult children or parents are not clubbed. Ask a CA before restructuring family investments.
11. Tax-loss harvesting and the anti-avoidance rules
Tax-loss harvesting is the mirror image: redeem lots that are below cost, book the loss, and use it to cancel gains taxed this year. You then reinvest in a similar but different fund, so your market exposure barely changes.
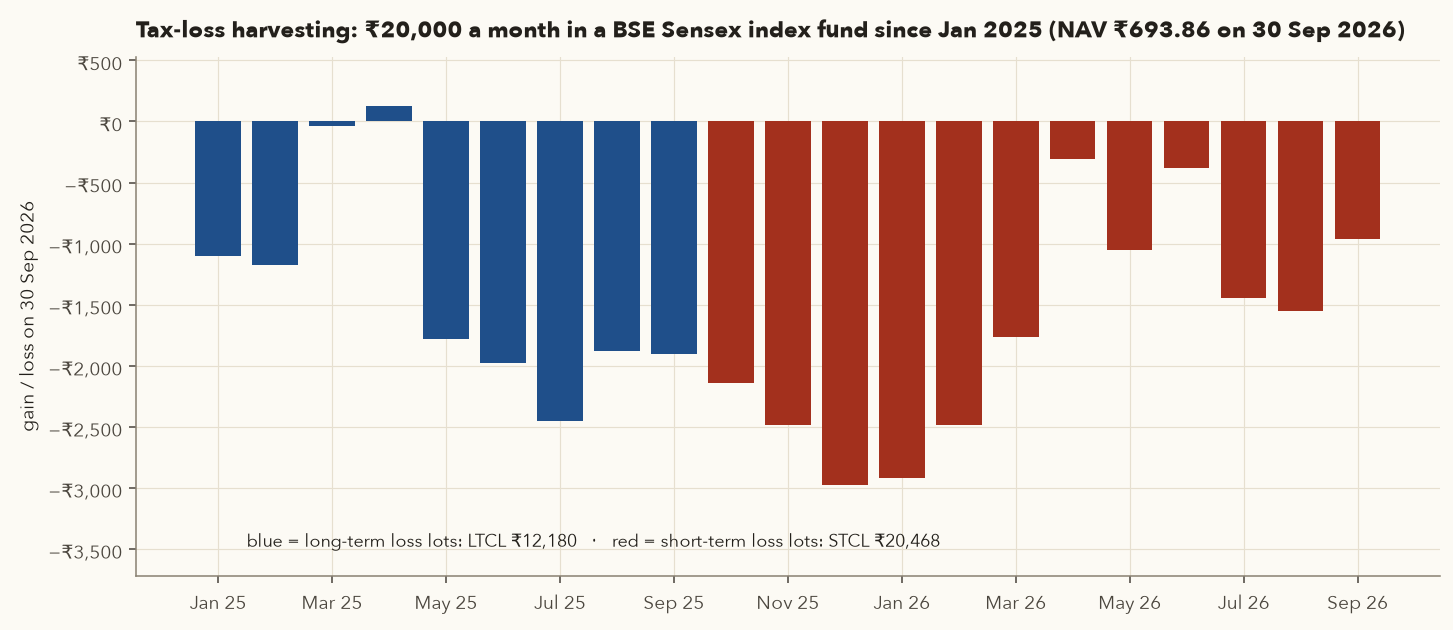
Booking ₹32,647 of losses on 30 Sep 2026
- 21 lots, ₹4,20,000 invested, worth ₹3,87,353 at NAV ₹693.862. 20 of the 21 lots are below cost.
- Redeem the whole folio. Lots from Jan–Sep 2025 are long-term: LTCL ₹12,180. Lots from Oct 2025 are short-term: STCL ₹20,468. STT ₹3.87.
- Reinvest the same day in a different Nifty 50 or Sensex index fund from another fund house. Your exposure is almost unchanged.
- Value: the STCL against a gain taxed at a 20% slab (or equity STCG at 20%) saves ₹4,257; at a 30% slab it would save ₹6,386. The LTCL can only absorb long-term gains: against 12.5% gains it saves ₹1,583.
The 2016 Nifty SIP from part 10 (never harvested) also has 25 lots in loss on 30 Sep 2026, starting with the 5 Jul 2024 lot, worth ₹17,332 of losses in total. But FIFO means you cannot reach them without first redeeming the older lots, which carry ₹9,45,945 of gains. Loss harvesting works only on a fund (or folio) where the losses are not stuck behind gains. Some investors start new SIPs in a fresh folio or a second fund house for this flexibility. Registrars apply FIFO within a folio, but confirm the treatment with your CA.
Is this legal? Wash sales, GAAR and stripping rules
- No wash-sale rule. India has no rule like the US one that disallows a loss if you buy back within 30 days. A genuine sale at a real loss is a real loss.
- Substance still matters. Courts can disregard a "colourable device" whose only purpose is to avoid tax (the McDowell doctrine). The General Anti-Avoidance Rule (GAAR, Chapter XI of the new Act from s.178, old Chapter X-A) applies only where the tax benefit in a year exceeds ₹3 crore, so it will not touch a retail investor's harvesting. Keep it clean: real redemptions, real purchases, a record of why, and preferably a different fund for the re-purchase after loss harvesting.
- Bonus stripping (s.175(9)–(10), old s.94(8)): if you buy units within 3 months before a record date, receive bonus units, and sell the original units within 9 months at a loss while keeping the bonus units, the loss is ignored and added to the cost of the bonus units. Bonus units in mutual funds are rare now, but the rule exists.
- Dividend stripping (s.175(8), old s.94(7)): a loss on units bought within 3 months before a record date and sold within 9 months after it is ignored up to the IDCW received, but only if that IDCW was exempt. Since IDCW became taxable in 2020 this rarely applies. Buying just before an IDCW still makes no sense: the NAV drops by the payout and you pay slab tax on it.
12. Debt, gold and international funds; the year-end calendar
Gain harvesting only helps where there is an exemption to use. That means equity-oriented funds and shares. For other classes:
- Specified (post-2023) debt funds: gains are slab income whenever you sell. Harvesting gains brings tax forward and saves nothing. Loss harvesting is rare (debt NAVs seldom fall), but a loss would be an STCL usable against anything.
- Gold, silver, international, pre-2023 debt (other class): LTCG is 12.5% with no exemption, so harvesting gains just brings the 12.5% forward. Harvesting losses works as for equity.
- Low-income family members are the exception. A resident whose other income is below the ₹4 lakh basic exemption can use the unused part against STCG and LTCG (basic-exemption adjustment, s.196(2), s.197(2), s.198(3)). And the ₹12 lakh rebate covers slab-taxed debt-fund gains but not the 12.5% rate.
₹3 lakh of debt-fund gain versus ₹3 lakh of gold LTCG
- Debt-fund gain (slab): total income ₹9 lakh. Slab tax = 5% × 4 L + 10% × 1 L = ₹30,000. Total income is within ₹12 lakh, so the rebate wipes it out: tax ₹0.
- Gold LTCG (12.5%): the rebate does not cover special-rate tax, and the pension already uses the basic exemption. Tax = 3,00,000 × 12.5% × 1.04 = ₹39,000.
For this parent, the "worse" debt-fund rule is better. Whose name an investment sits in matters, but money you gift to a parent and the income on it is theirs (no clubbing for parents). Get a CA's view for large amounts.
Year-end calendar
| When | What to do |
|---|---|
| January | Download the capital-gains statement (part 16). Total your realised STCG/LTCG for the year so far, from all brokers and both registrars. |
| February – mid-March | Plan harvests: unused exemption, exit-load dates, lots that turn long-term soon, loss lots worth booking. Check that a loss lot is not stuck behind gain lots (FIFO). |
| By about 25 March | Place redemptions. For equity funds the cut-off is 3 pm for that day's NAV. The sale date (the NAV date) decides the tax year, not the date the money arrives (usually 2–3 working days later). ETFs settle T+1. |
| 31 March 2027 (a Wednesday) | Last day for tax year 2026-27. Do not leave it to this day: a holiday, a missed cut-off or a payment that does not reach the AMC in time pushes the transaction into the next year. |
| April | A new exemption. If you have large long-term gains to realise, splitting them across late March and early April uses two exemptions. |
13. Tax-saving products: ELSS, NPS, PPF, EPF, SSY, SGB
"Tax-saving" products give a deduction from taxable income when you invest. Almost all of them work only under the old regime, which you must choose actively. The new regime (s.202, old s.115BAC) is the default and gives lower slabs and a ₹75,000 standard deduction instead.
ELSS and s.123 (old s.80C)
An ELSS (equity-linked savings scheme) is an equity fund with a 3-year lock-in per instalment. Investments in it count towards the ₹1.5 lakh deduction under s.123 and Schedule XV (old s.80C), along with EPF contributions, PPF, life-insurance premiums, home-loan principal, SSY, tax-saver FDs and children's tuition fees. When you redeem, ELSS is taxed as an ordinary equity fund. Varsity's ELSS chapter predates the new regime's dominance; the key question now is whether you should be in the old regime at all.
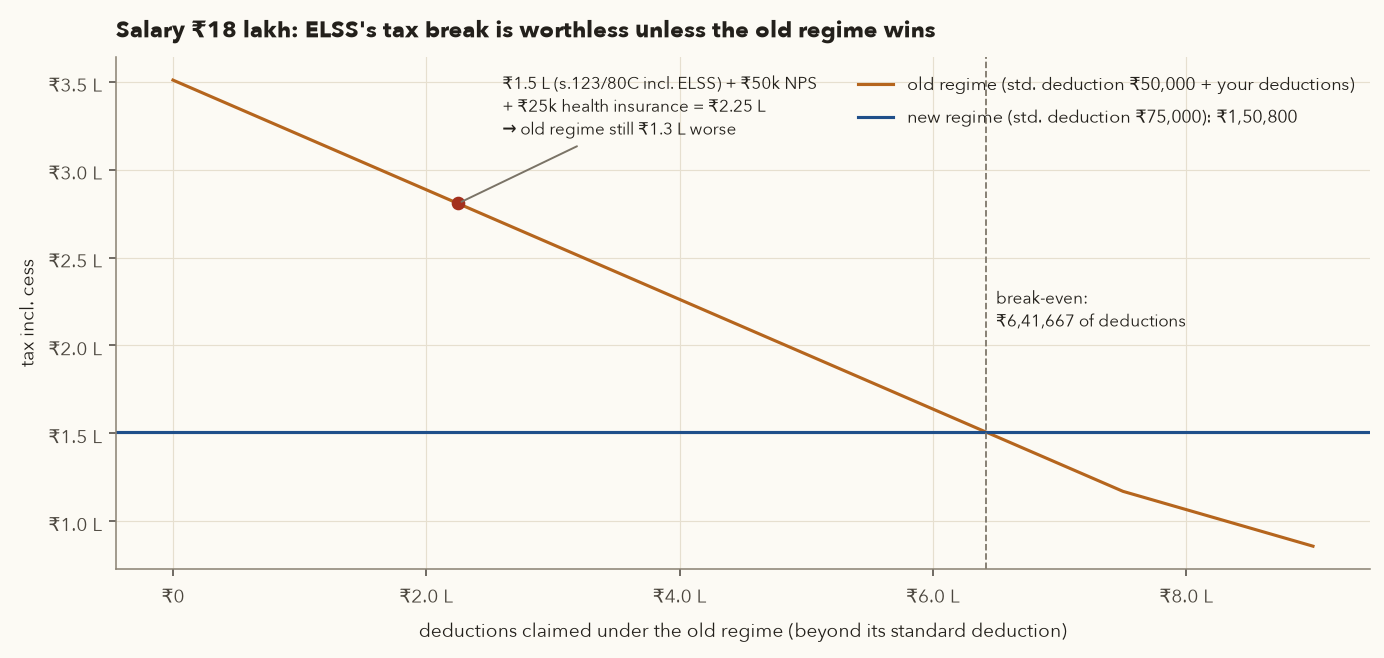
Does ELSS still save tax?
- New regime: 18,00,000 − 75,000 = ₹17,25,000. Tax = 20,000 + 40,000 + 60,000 + 20% × 1,25,000 = 1,45,000; with cess ₹1,50,800.
- Old regime with typical deductions: ₹1.5 lakh under s.123 (EPF plus ELSS), ₹50,000 own NPS contribution (old 80CCD(1B)), ₹25,000 health insurance (old 80D) = ₹2.25 lakh. Taxable = 18,00,000 − 50,000 − 2,25,000 = ₹15,25,000. Tax = 12,500 + 1,00,000 + 30% × 5,25,000 = 2,70,000; with cess ₹2,80,800.
- The old regime costs ₹1,30,000 more. It would need ₹6,41,667 of deductions to break even (possible with large home-loan interest and a house rent allowance (HRA) claim, rare otherwise).
- Inside the old regime, ELSS's ₹1.5 lakh is worth up to 31.2% (₹46,800). In the new regime it is worth nothing. It is still a fine equity fund, but with a lock-in you may not want.
NPS: the deduction that survives in the new regime
Your employer's contribution to your NPS account is deductible up to 14% of basic salary plus dearness allowance (DA) in the new regime (10% in the old) under s.124 (old s.80CCD(2)). Your own contributions (old 80CCD(1) and the extra ₹50,000 of 80CCD(1B)) help only in the old regime. Combined employer contributions to NPS, EPF and superannuation above ₹7.5 lakh a year are taxable. If your employer offers it, restructuring ₹1,00,800 a year (14% of a ₹7.2 lakh basic) into employer NPS cuts the new-regime tax in our example from ₹1,50,800 to ₹1,29,834, saving ₹20,966, in exchange for money locked until 60. At exit, 60% of the corpus can be withdrawn tax-free and the annuity income is taxed at slab. PFRDA's newer exit options allow larger lump sums; their tax treatment is less settled, so check before you exit.
The debt-side comparison
| Product | Rate (Oct–Dec 2026) | Tax on returns | Lock-in / notes |
|---|---|---|---|
| PPF | 7.1% | Interest and withdrawal tax-free; the deposit is also deductible in the old regime (together called "EEE", exempt-exempt-exempt) | 15 years; ₹1.5 lakh/year cap |
| Sukanya Samriddhi (SSY) | 8.2% | Exempt; deposit deductible in old regime | For a daughter under 10; matures at 21 |
| EPF | Declared yearly by EPFO | Exempt, except interest on your own contributions above ₹2.5 lakh a year | Retirement; withdrawals before 5 years of service taxable |
| Debt fund (post-2023) | Market-linked | Slab on the gain, only when you redeem | None; exit loads vary |
| Bank FD | e.g. SBI 1 yr 6.25% | Slab, every year as interest accrues; TDS | Premature-withdrawal penalty |
For a long-term debt allocation, PPF's tax-free 7.1% beats a fully taxed debt fund for anyone above the 5% slab, as long as you can live with the lock-in and the cap.
Sovereign Gold Bonds (SGBs)
SGBs pay 2.5% a year interest (taxed at slab) plus the gold price. From 1 Apr 2026 (Budget 2026, s.70(1)(x)), the capital gain at redemption is exempt only if you subscribed at the original issue and held continuously until maturity (8 years). Bonds bought on the exchange, or redeemed early through RBI's window after 5 years, are now taxed: 12.5% LTCG if held more than 12 months (they are listed), slab otherwise. No new SGB tranches have been issued since February 2024.
14. Where to park cash: arbitrage vs liquid fund vs FD
Money for a near-term goal or an emergency fund wants safety and liquidity. Three common homes, each taxed differently:
- Arbitrage fund: buys shares and sells futures on them, earning the small gap. Returns are close to a liquid fund, but it is an equity-oriented fund: 20% if sold within 12 months, 12.5% after (inside the ₹1.25 lakh exemption if unused). Varsity calls this "the real arbitrage is the tax arbitrage". Returns can dip when futures premiums shrink, and many charge a small exit load within 30 days.
- Liquid fund: very short-term debt. Specified MF: slab rate on the gain.
- Bank FD: interest taxed at slab every year as it accrues.
- \(r_{\text{pre}}\)
- The return over the whole holding period before tax, in % (not annualised): for a fund, sale NAV ÷ buy NAV − 1; for an FD, the interest earned.
- \(t\)
- The tax rate on that return: your slab rate for a liquid fund or FD; 20% (12 months or less) or 12.5% (more than 12 months) for an arbitrage fund.
- \(1.04\)
- Adds the 4% cess, so a 30% slab really takes 31.2%.
- \(r_{\text{post}}\)
- What you keep after tax, in % over the same period.
How it works: \(t \times 1.04\) is the share of the gain that goes in tax; \(1 - t \times 1.04\) is the share you keep. Multiply the pre-tax return by it. It assumes the whole gain is taxed (for the arbitrage fund, that your ₹1.25 lakh exemption is already used up). The table below compares all three at each slab.
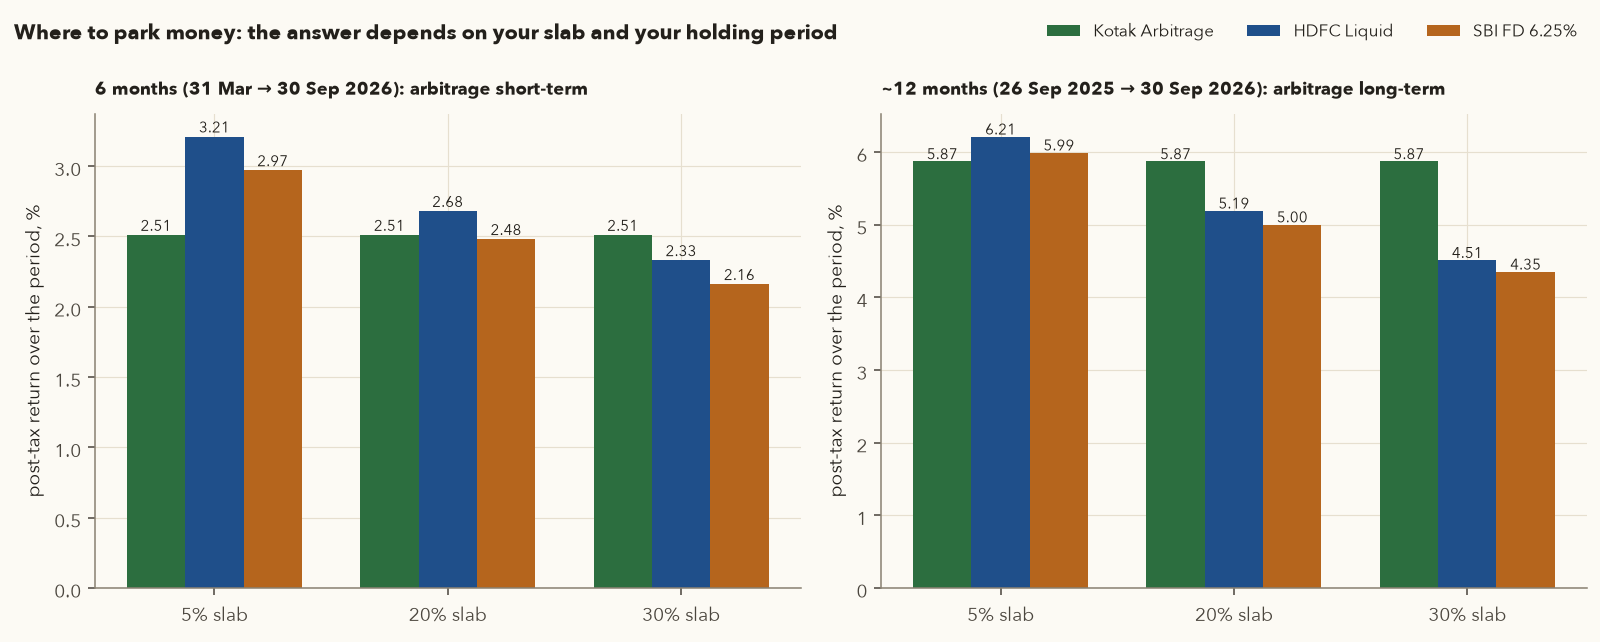
Two holding periods ending 30 Sep 2026
| Period | Arbitrage (pre-tax) | Liquid (pre-tax) | FD (pre-tax) | Post-tax at 5% slab arb / liquid / FD | at 20% | at 30% |
|---|---|---|---|---|---|---|
| 31 Mar → 30 Sep 2026 (183 days; arbitrage short-term, 20%) | 3.16% | 3.39% | 3.13% | 2.51 / 3.21 / 2.97 | 2.51 / 2.68 / 2.48 | 2.51 / 2.33 / 2.16 |
| 26 Sep 2025 → 30 Sep 2026 (369 days; arbitrage long-term, 12.5%) | 6.75% | 6.55% | 6.32% | 5.87 / 6.21 / 5.99 | 5.87 / 5.19 / 5.00 | 5.87 / 4.51 / 4.35 |
- Arbitrage NAV ₹40.6185 → ₹43.3592 over 369 days = 6.75%. Long-term: 6.75 × (1 − 0.125 × 1.04) = 5.87% (assuming the exemption is already used; if not, the gain is tax-free).
- Liquid NAV ₹5,249.11 → ₹5,593.11 = 6.55%. At a 30% slab: 6.55 × (1 − 0.312) = 4.51%.
- Under 12 months the arbitrage fund's 20% beats the liquid fund only for the 30% slab, and then barely (2.51% vs 2.33%). Held over 12 months it wins clearly for the 20% and 30% slabs.
- Exactly 12 months is still short-term: 30 Sep 2025 → 30 Sep 2026 would have been taxed at 20%.
15. Special cases: NRIs, minors, gifts, inheritance
| Situation | What happens |
|---|---|
| NRI redeems units | Same tax classes and rates. The AMC deducts TDS on the gain at the applicable rate (for example 20% on equity STCG, 12.5% on equity LTCG above the exemption, slab-equivalent rates on specified-MF gains), plus surcharge and cess. IDCW to NRIs: 20% TDS or the lower treaty rate with a tax-residency certificate (s.393(2) Table Sl. 10, old s.196A). File a return to claim any excess. Some AMCs restrict US/Canada residents. |
| Investing in a minor child's name | The child's income (including capital gains) is clubbed with the parent who earns more (s.99(1)(c), old s.64(1A)), except ₹1,500 per child per year (Schedule III, Sl. 17, old s.10(32)). The exemption is not doubled. Clubbing stops once the child turns 18. |
| Gifting units | A gift is not a "transfer" for capital gains (s.70(1)(b)), so no tax for you. Gifts from relatives are tax-free for the receiver. The receiver takes over your cost and your holding period (s.73(1) Sl. 1; s.2(101)(c)(B)(I)). Gifts to a spouse or minor child: later income and gains are clubbed with you. Units in demat move by off-market transfer; units held in statement form can now be transferred online through CAMS, KFintech or MF Central (not for ETFs; redemption blocked for 10 days after transfer). |
| Inheritance (transmission) | No tax when units pass to a nominee or legal heir. The heir's cost is the original owner's cost and the holding period includes the original owner's. Grandfathering carries over too. |
16. Reporting: statements, AIS and the ITR
- Capital-gains statement. Download it for the tax year from CAMS (for funds it services) and KFintech (for the rest), or from MF Central, which covers both. It lists every redemption lot by lot, with purchase date, NAV, grandfathered value where relevant, and STCG/LTCG. ETF and share sales come from your broker's tax P&L.
- Consolidated Account Statement (CAS) from NSDL/CDSL or the registrars: all your holdings across fund houses and demat. Useful to check nothing is missing.
- AIS (Annual Information Statement) and Form 26AS on the e-filing portal show redemptions and IDCW reported by the registrars, and TDS deducted. Reconcile them with the statements before filing.
- Which form. As for shares (Chapter 13, part 13): ITR-1/ITR-4 are allowed if your only capital gains are equity LTCG up to ₹1.25 lakh with no losses to carry forward; otherwise ITR-2 (ITR-3 if you also have F&O or business income). Equity LTCG goes scrip by scrip (fund by fund) in the schedule known as Schedule 112A in the forms filed in 2026; the CBDT notifies new forms under the 2025 Act, so check the portal for the year you file.
- File by the due date (31 July for ITR-2) to carry losses forward.
17. A full year for one investor
Meera is a salaried resident with a ₹18 lakh salary, on the new regime. Her employer deducts TDS on salary. Everything below is real NAVs and prices; all dates fall in tax year 2026-27 (to 30 Sep 2026, with nothing else happening later in the year).
| Event | Details (real data) | Gain / income | Class and rate |
|---|---|---|---|
| (a) Car down-payment, 3 Aug 2026 | Redeems ₹4,00,000 from her ₹20,000-a-month UTI Nifty 50 Index Fund SIP (since Jan 2019) at NAV ₹174.4125: 2,293.41 units from 9 lots (Jan–Sep 2019), all long-term | 2,30,296.62 | Equity LTCG |
| (b) Debt fund bought 2022 | HDFC Corporate Bond, ₹4 L on 15 Jun 2022, redeemed 15 Jun 2026 (part 3) | 1,33,933.91 | Other LTCG 12.5% |
| (c) Debt fund bought 2024 | Same fund, ₹4 L on 14 Jun 2024, redeemed 15 Jun 2026 | 59,223.41 | Specified MF: slab |
| (d) Gold ETF | 3,000 GOLDBEES bought 1 Apr 2025 at ₹76.72, sold 15 Sep 2026 at ₹123.62 | 1,40,700.00 | Other LTCG 12.5% |
| (e) International FoF | Motilal Oswal Nasdaq 100 FoF, ₹2 L on 1 Jul 2025 at ₹40.6147, redeemed 1 Jul 2026 at ₹69.6296 to "rebalance" | 1,42,861.65 | Other, under 24 months: slab |
| (f) IDCW | 40,000 units of ICICI Pru BAF Monthly IDCW, ₹0.07 × 6 payouts (Apr–Sep 2026) | 16,800.00 | Slab; TDS ₹1,680 |
| (g) Switch regular → direct, 4 May 2026 | UTI Nifty 50 Index Fund Regular, ₹3 L invested 1 Jun 2020 at ₹64.5172 (4,649.923 units), switched at ₹166.1212 = ₹7,72,451 | 4,72,450.79 | Equity LTCG |
| (h) "Harvest", 1 Sep 2026 | Sells 1,359.74 SIP units at ₹169.3801 to book "₹1.25 lakh tax-free", buys back | 1,25,000.00 | Equity LTCG |
She also runs a ₹20,000 SIP in the HDFC BSE Sensex Index Fund since Jan 2025 (part 11), untouched in the baseline.
What Meera owes as things stand
- Slab income = salary after standard deduction ₹17,25,000 + IDCW ₹16,800 + debt-fund gain (c) ₹59,223.41 + Nasdaq FoF gain ₹1,42,861.65 = ₹19,43,885.06. Slab tax = 20,000 + 40,000 + 60,000 + 20% × 3,43,885.06 = ₹1,88,777.01.
- Other-class LTCG = 1,33,933.91 + 1,40,700 = ₹2,74,633.91 × 12.5% = ₹34,329.24.
- Equity LTCG = 2,30,296.62 + 4,72,450.79 + 1,25,000 = ₹8,27,747.41. Taxable above ₹1,25,000: ₹7,02,747.41 × 12.5% = ₹87,843.43.
- Total = (1,88,777.01 + 34,329.24 + 87,843.43) × 1.04 = ₹3,23,387.66. Her salary alone would cost ₹1,50,800, so the investments add ₹1,72,587.66.
- The "harvest" in (h) was a mistake: the car redemption had already used the exemption, so the ₹1.25 lakh it booked was taxed at 12.5%.
Same goals, five different choices
- Skip the harvest: the exemption was already used. Saves ₹16,250 this year (it only brought forward tax on a gain she would have paid later anyway).
- Defer the regular → direct switch to future Aprils, switching about ₹1.25 lakh of gain each year in which the exemption is otherwise unused (the ₹4.72 lakh gain needs about 3.8 years of exemptions). The cost of staying in the regular plan meanwhile is the expense gap: about 0.13% a year from the two plans' NAVs, roughly ₹1,017 a year on ₹7.72 lakh. Saves ₹61,419 this year.
- Hold the Nasdaq FoF past 24 months (after 1 Jul 2027) and rebalance by directing new money elsewhere (Chapter 16). Saves ₹29,715 this year. When she sells later, she pays 12.5% instead of slab, so ₹11,143 of that is a permanent saving if the gain stays the same.
- Growth + SWP instead of IDCW: the same ₹16,800 withdrawn from the growth option carries only ₹5,596 of gain. Saves ₹2,767.
- Tax-loss harvest the Sensex fund on 30 Sep 2026 and reinvest in another Nifty 50 fund: STCL ₹20,468 cancels part of the slab-taxed debt-fund gain; LTCL ₹12,180 cancels part of the gold LTCG. Saves ₹5,841.
New computation. Slab income = 17,25,000 + (59,223.41 − 20,467.61) = ₹17,63,755.80 → slab tax ₹1,52,751.16. Other LTCG = 2,74,633.91 − 12,179.76 = ₹2,62,454.15 → ₹32,806.77. Equity LTCG = 2,30,296.62 + 5,596.49 = ₹2,35,893.11 → (2,35,893.11 − 1,25,000) × 12.5% = ₹13,861.64. Total × 1.04 = ₹2,07,396.35, of which investments add ₹56,596.35.
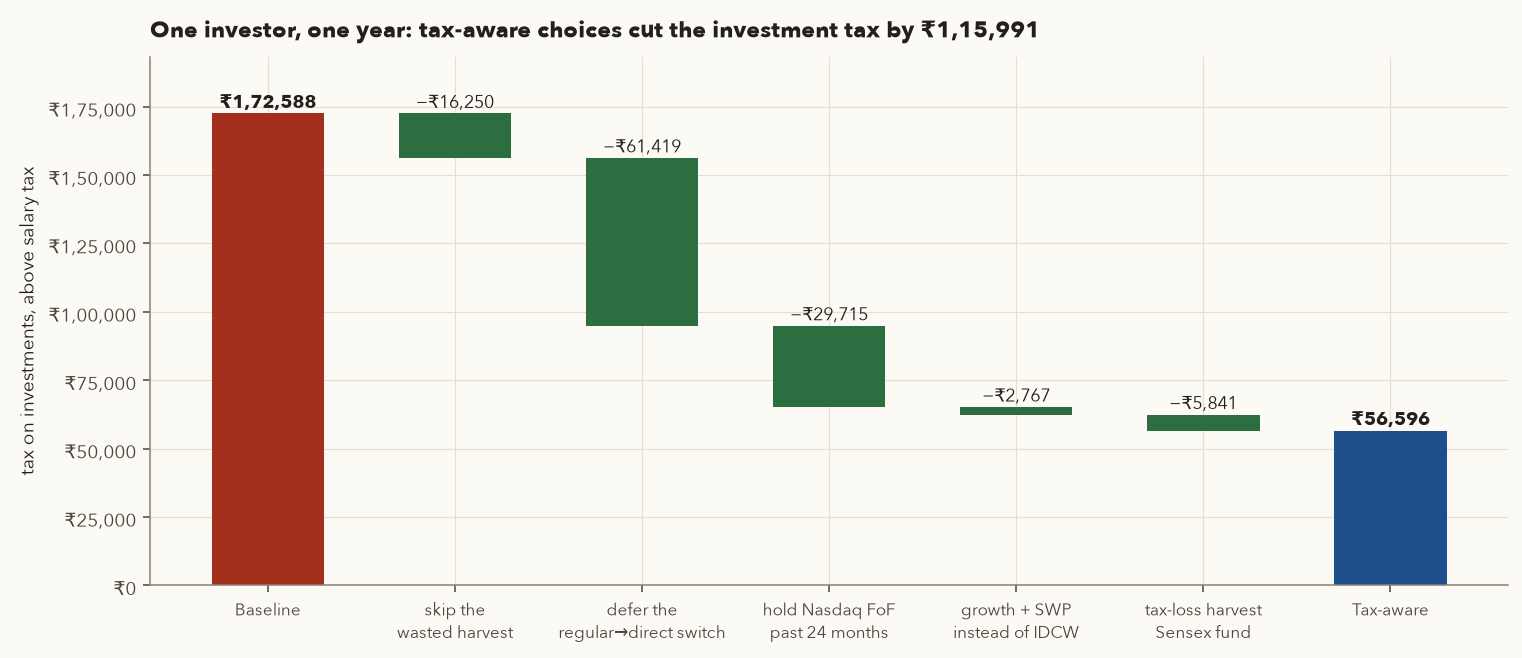
course/scripts/ch15_figures.py.Most of this year's ₹1,15,991 is tax postponed, not tax avoided. The switch gain will be taxed when switched. Only the slices that land inside future unused exemptions escape for good. The Nasdaq and loss-harvest gains will be taxed later, at 12.5%. The truly permanent parts are the rate differences (slab versus 12.5%), the IDCW-to-SWP change, and any exemption that would otherwise lapse. Deferral is still worth having: the postponed tax keeps compounding for you. But never let tax steer you into an investment you do not want. If Meera needed the Nasdaq money in July, selling was right.
18. In your framework, and try it yourself
framework.funds implements this chapter. fund_tax_class(category, equity_pct, debt_pct, purchase_date) returns 'equity_oriented', 'specified_debt' or 'other' under 2026-27 rules. fund_capital_gains(lots, sell_date, sell_units, sell_nav, tax_class, slab_rate, ltcg_exemption_left, grandfather_nav_31jan2018) does the lot-by-lot FIFO computation of part 5 and returns the STCG/LTCG and tax with cess. harvest_plan(lots, nav_today, today, tax_class, exemption_left) lists the units to redeem to use the exemption and the loss lots available (with how many older units FIFO forces you to redeem first). sip_simulate builds the lots from real NAVs fetched with load_nav(scheme_code), and rebalance_backtest(..., tax=True) charges tax on rebalancing trades (Chapter 16). Rates, holding periods, STT, stamp duty and the IDCW TDS threshold live in framework/config.py with sources and an MF_AS_OF date. From the command line: python -m framework.funds tax --help and python -m framework.funds harvest --help.
Run these from the repository root (for example .venv/bin/python snippet.py). Snippet 1 uses the framework; snippets 2 and 3 need only pandas and the NAV files this chapter saved in data/extra/.
1. FIFO gains and a harvest plan with the framework (reproduces part 5):
import sys; sys.path.insert(0, ".")          # run from the repository root, so framework/ is importable
from framework.funds import load_nav, sip_simulate, fund_capital_gains, harvest_plan

nav = load_nav(120716)                        # UTI Nifty 50 Index Fund - Direct - Growth (cached in data/mf/)
sip = sip_simulate(nav, 10_000, "2023-01-01", end="2026-09-30", day=5)
lots = sip["lots"]                            # one row per instalment: date, nav, amount, units
sell_nav = nav.loc["2026-09-30"]
units = 200_000 / sell_nav                    # redeem Rs 2,00,000 on 30 Sep 2026
detail, summary = fund_capital_gains(lots, "2026-09-30", units, sell_nav, "equity_oriented")
print(detail.round({"units": 2, "gain": 2})[["buy_date", "units", "term", "gain"]].tail(3))
print({k: summary[k] for k in ["units", "ltcg", "stcg", "tax", "stt"]})
plan = harvest_plan(lots, sell_nav, "2026-09-30", "equity_oriented")
print(plan["note"], "| loss lots:", len(plan["loss_lots"]))
# -> ltcg about 31,572 (the framework ignores the small stamp duty in cost; part 5 gets 31,563.26), tax 0.0, 25 loss lots
2. A self-contained FIFO redemption (pandas only):
import pandas as pd

nav = pd.read_csv("data/extra/ch15_mf_120716_uti_nifty50_dir.csv", parse_dates=["date"]).set_index("date")["nav"]

def sip_lots(nav, amount, start, end, day=5, stamp=0.00005):
    rows = []
    for m in pd.date_range(start, end, freq="MS"):
        d = nav.index[nav.index.searchsorted(m.replace(day=day))]      # first NAV on/after the SIP date
        rows.append({"date": d, "amount": amount, "units": round(amount * (1 - stamp) / nav[d], 3)})
    return pd.DataFrame(rows)

def fifo(lots, sell_date, sell_nav, amount):
    left, out = amount / sell_nav, []
    for r in lots.itertuples():
        if left <= 0:
            break
        u = min(r.units, left); left -= u
        lt = pd.Timestamp(sell_date) > r.date + pd.DateOffset(months=12)
        out.append({"buy": r.date.date(), "units": u, "gain": u * sell_nav - u * r.amount / r.units,
                    "term": "LT" if lt else "ST"})
    return pd.DataFrame(out)

lots = sip_lots(nav, 10_000, "2023-01-01", "2026-09-30")
red = fifo(lots, "2026-09-30", nav["2026-09-30"], 200_000)
print(len(lots), "lots;", len(red), "used;", red.groupby("term")["gain"].sum().round(2).to_dict())
# -> 45 lots; 17 used; {'LT': 31563.26}
3. SWP gain portion and IDCW comparison (pandas only):
import pandas as pd

nav = pd.read_csv("data/extra/ch15_mf_120716_uti_nifty50_dir.csv", parse_dates=["date"]).set_index("date")["nav"]
buy_d = nav.index[nav.index.searchsorted(pd.Timestamp("2023-04-03"))]
units0 = round(1_000_000 * (1 - 0.00005) / nav[buy_d], 3)
cost_per_unit = 1_000_000 / units0
rows = []
for m in pd.date_range("2024-05-01", "2026-09-30", freq="MS"):
    d = nav.index[nav.index.searchsorted(m.replace(day=10))]
    rows.append({"date": d, "gain": 15_000 * (1 - cost_per_unit / nav[d])})
swp = pd.DataFrame(rows)
swp["fy"] = swp.date.apply(lambda d: d.year if d.month >= 4 else d.year - 1)
print(swp.groupby("fy")["gain"].sum().round(2))         # 2024: 46197.34, 2025: 57843.06, 2026: 26489.85
print("gain share of cash withdrawn:", round(swp.gain.sum() / (15_000 * len(swp)) * 100, 2), "%")   # 30.01 %
19. Practical checklist
- For every fund you hold, note its tax class (equity-oriented, specified, other) and, for debt funds, whether each lot was bought before or after 1 Apr 2023.
- Choose the growth option. If you need income, set up an SWP rather than an IDCW plan (unless your income is within the rebate limit).
- Before any redemption or switch, download the registrar's capital-gains statement and see which lots FIFO will take, their term and gain.
- Treat switches, STPs and regular → direct moves as sales. Spread a large switch across tax years to fit the ₹1.25 lakh exemption.
- Check exit-load dates. Do not harvest lots that still carry a load unless the gain exceeds about 7% (1% load) of the value sold.
- In February–March: total the year's equity LTCG from all sources, then harvest the unused exemption on long-term lots. Never harvest grandfathered units below their 31 Jan 2018 NAV.
- Book losses on funds in loss when you have gains to absorb, especially slab-taxed gains. Reinvest in a similar but different fund. Keep a record.
- Place year-end transactions by about 25 March, before the 3 pm cut-off.
- Compare the old and new regimes each year before buying ELSS or other 80C-style products. Ask your employer about NPS under s.124.
- For gold or international exposure you may need within 2 years, prefer a listed ETF (12-month rule) over a FoF (24-month rule).
- Reconcile AIS and Form 26AS with your statements, and file by the due date to carry losses forward.
- Keep records: statements, contract notes, harvest notes, gift deeds. Ask a CA for anything large or unusual.
20. Key takeaways
- Funds are pass-through: trades inside the fund are not taxed; you pay only on redemption or IDCW. A fund with at least 65% Indian equity is taxed entirely as equity.
- Three classes for 2026-27: equity-oriented (20% / 12.5% above ₹1.25 L after 12 months), specified MF bought from Apr 2023 (slab, always), and other (12.5% after 12 months if listed or 24 months if unlisted; slab before that). No indexation since 23 Jul 2024.
- Each SIP instalment is a separate lot, and redemptions go FIFO, per folio, scheme, plan and option.
- Switches, STPs and regular → direct moves are taxable sales. Scheme mergers, segregation, gifts and inheritance are not.
- An SWP is taxed only on its gain portion; IDCW is taxed in full at slab. For most investors growth + SWP is cheaper.
- Harvesting the ₹1.25 lakh exemption every March left a ₹10,000 SIP since 2016 ₹87,045 richer after tax (tax due fell from ₹1,04,470 to ₹17,237). It fails when exit loads exceed the tax saved, and it must skip grandfathered units below their FMV.
- Tax-loss harvesting is legal (India has no wash-sale rule, but the anti-avoidance rules in part 11 apply), most valuable against slab-taxed gains, and blocked by FIFO when losses sit behind older gains.
- ELSS saves tax only in the old regime, which rarely wins at ₹18 lakh. Employer NPS is the main deduction left in the new regime.
- Much of what tax-aware investing "saves" in a year is deferral. Count the permanent part honestly, and never let tax override a needed sale.
21. Quiz and exercises
Q1. A Nifty 50 index fund, a gold ETF, a gold FoF and a corporate-bond fund bought in May 2024: which tax class is each in for a sale in tax year 2026-27?
Q2. A balanced-advantage fund shows 45% net equity but 72% gross equity (the rest hedged with futures). How is it taxed?
Q3. You bought units of an equity fund on 7 Oct 2025. On which date does a redemption first become long-term?
Q4. You hold 500 units of an equity fund bought on 10 Jan 2017 at NAV ₹40. The NAV on 31 Jan 2018 was ₹52. What is the taxable gain per unit if you redeem at (a) ₹90, (b) ₹48, (c) ₹35?
Q5. Your SIP has 30 lots. The oldest 10 are long-term with gains, the newest 20 are in loss. Can you redeem only the loss lots to book a short-term loss?
Q6. You withdraw ₹20,000 by SWP from an equity fund when the NAV is ₹250. Your cost is ₹160 per unit and the units are long-term. How much of the ₹20,000 is taxable gain, and what is the tax if your exemption is already used?
Q7. An investor in the 30% slab receives ₹60,000 of IDCW a year from an equity fund. What does it cost in tax compared with an SWP of ₹60,000 whose gain portion is 35%, if the exemption is unused?
Q8. You switch ₹6 lakh from the regular to the direct plan of the same index fund. Your cost was ₹3.5 lakh, bought in 2021. You have no other LTCG this year. What is the tax, and how could you reduce it?
Q9. In March you plan to harvest ₹1.25 lakh of LTCG from an active fund that charges 1% exit load within 2 years. The lots you would sell are 18 months old and show a 5% gain. Should you?
Q10. You have ₹80,000 of short-term loss from a fund. This year you also have ₹1,00,000 of slab-taxed gain from a debt fund bought in 2024 (30% slab) and ₹1,00,000 of equity LTCG. Where does the loss go?
Q11. Your salary is ₹14 lakh, new regime, with no deductions available in the old regime except ₹1.5 lakh of EPF + ELSS. Does buying ELSS save tax?
Q12. You need to park ₹5 lakh for 8 months and you are in the 30% slab. Liquid fund or arbitrage fund, if both return about 6.5% a year?
Q13. Exercise: download your capital-gains statement for last year from MF Central (or CAMS and KFintech). Classify each redemption by class and term, and compute the tax with the part 17 method. How much exemption did you leave unused?
22. Sources
Zerodha Varsity (concepts; explained here in our own words and updated where Varsity's figures are older): Markets and Taxation, ch. 4: Taxation for Investors (LTCG, STCG, indexation, FIFO; mentions the old 36-month debt rule) · ch. 3: Classifying your market activity · ch. 7: ITR forms · Personal Finance, Equity Scheme (Part 2): ELSS and s.80C · Arbitrage Funds ("the real arbitrage is the tax arbitrage") · Exchange-traded funds (ETF) · The Debt Funds (Part 4) · NPS tax rules & benefits (80CCD(1), (1B), (2); 14% in the new regime; ₹7.5 lakh cap).
Law and official sources (checked 2 Oct 2026): Income-tax Act, 2025 (Gazette): s.2(101) holding periods; s.70(1)(b), (x), (zj), (zk); s.73(1) Table Sl. 1, 8, 10–12; s.76 specified MF; s.90(7)–(8) grandfathering; s.99 clubbing; s.123 and Schedule XV; s.124; s.156 rebate; s.175(8)–(10); Chapter XI GAAR; s.196–198 and s.198(8); s.202; s.393(1) Table Sl. 4 and s.393(2) Table Sl. 10; Schedule III Sl. 17; Schedule VII · Income-tax Act, 2025 as amended by Finance Act, 2026 (Income Tax Department) · Income Tax Department: old s.50AA and the specified-MF definition from 1 Apr 2025 · Memorandum explaining the Finance Bill, 2026 (no interest deduction against IDCW/dividends; SGB exemption restricted to original subscribers held to maturity) · AMFI: Tax regime for mutual funds · AMFI best-practice guideline 116: transfer of units held in SoA mode (Aug 2024).
Secondary sources used to cross-check rates and practice: ClearTax: STT rates (0.001% on equity fund/ETF sales; unchanged by Budget 2026) · ClearTax: SGB capital gains from 1 Apr 2026 · Taxmann: Budget 2026 curtails SGB tax-free status · Taxguru: TDS on MF income raised to ₹10,000 (Budget 2025) · Taxguru: interest deduction barred against dividend/MF income (Budget 2026) · Upstox: Budget 2026 and mutual-fund taxation · Angel One: income-plus-arbitrage FoFs, 12.5% after 24 months · Upstox: ICICI Pru BAF IDCW ₹0.07 per unit (2026) · INDmoney: Parag Parikh Flexi Cap exit load · INDmoney: UTI Nifty 50 Index Fund, exit load nil, TER 0.20% · Paisabazaar: SBI FD rates, September 2026 · Small-savings rates for Oct–Dec 2026 (PPF 7.1%, SSY 8.2%) · Motilal Oswal: TDS for NRIs, 2026.
Data: daily NAVs from AMFI via mfapi.in, saved as data/extra/ch15_mf_<code>_*.csv (UTI Nifty 50 Index Direct 120716 and Regular 100822; Parag Parikh Flexi Cap 122639; Kotak Arbitrage 119771; HDFC Liquid 119091; HDFC Corporate Bond 118987; Motilal Oswal Nasdaq 100 FoF 145552; ICICI Pru BAF Growth 120377 and Monthly IDCW 122236; HDFC BSE Sensex Index 119065; Nippon India Gold Savings 118663), to 30 Sep 2026. GOLDBEES closes from NSE via Yahoo Finance (data/extra/GOLDBEES.csv). All calculations and figures: course/scripts/ch15_figures.py with course/scripts/ch15_lib.py; numbers saved to data/extra/ch15_numbers.json. Examples are historical analysis for education, not recommendations or tax advice.